

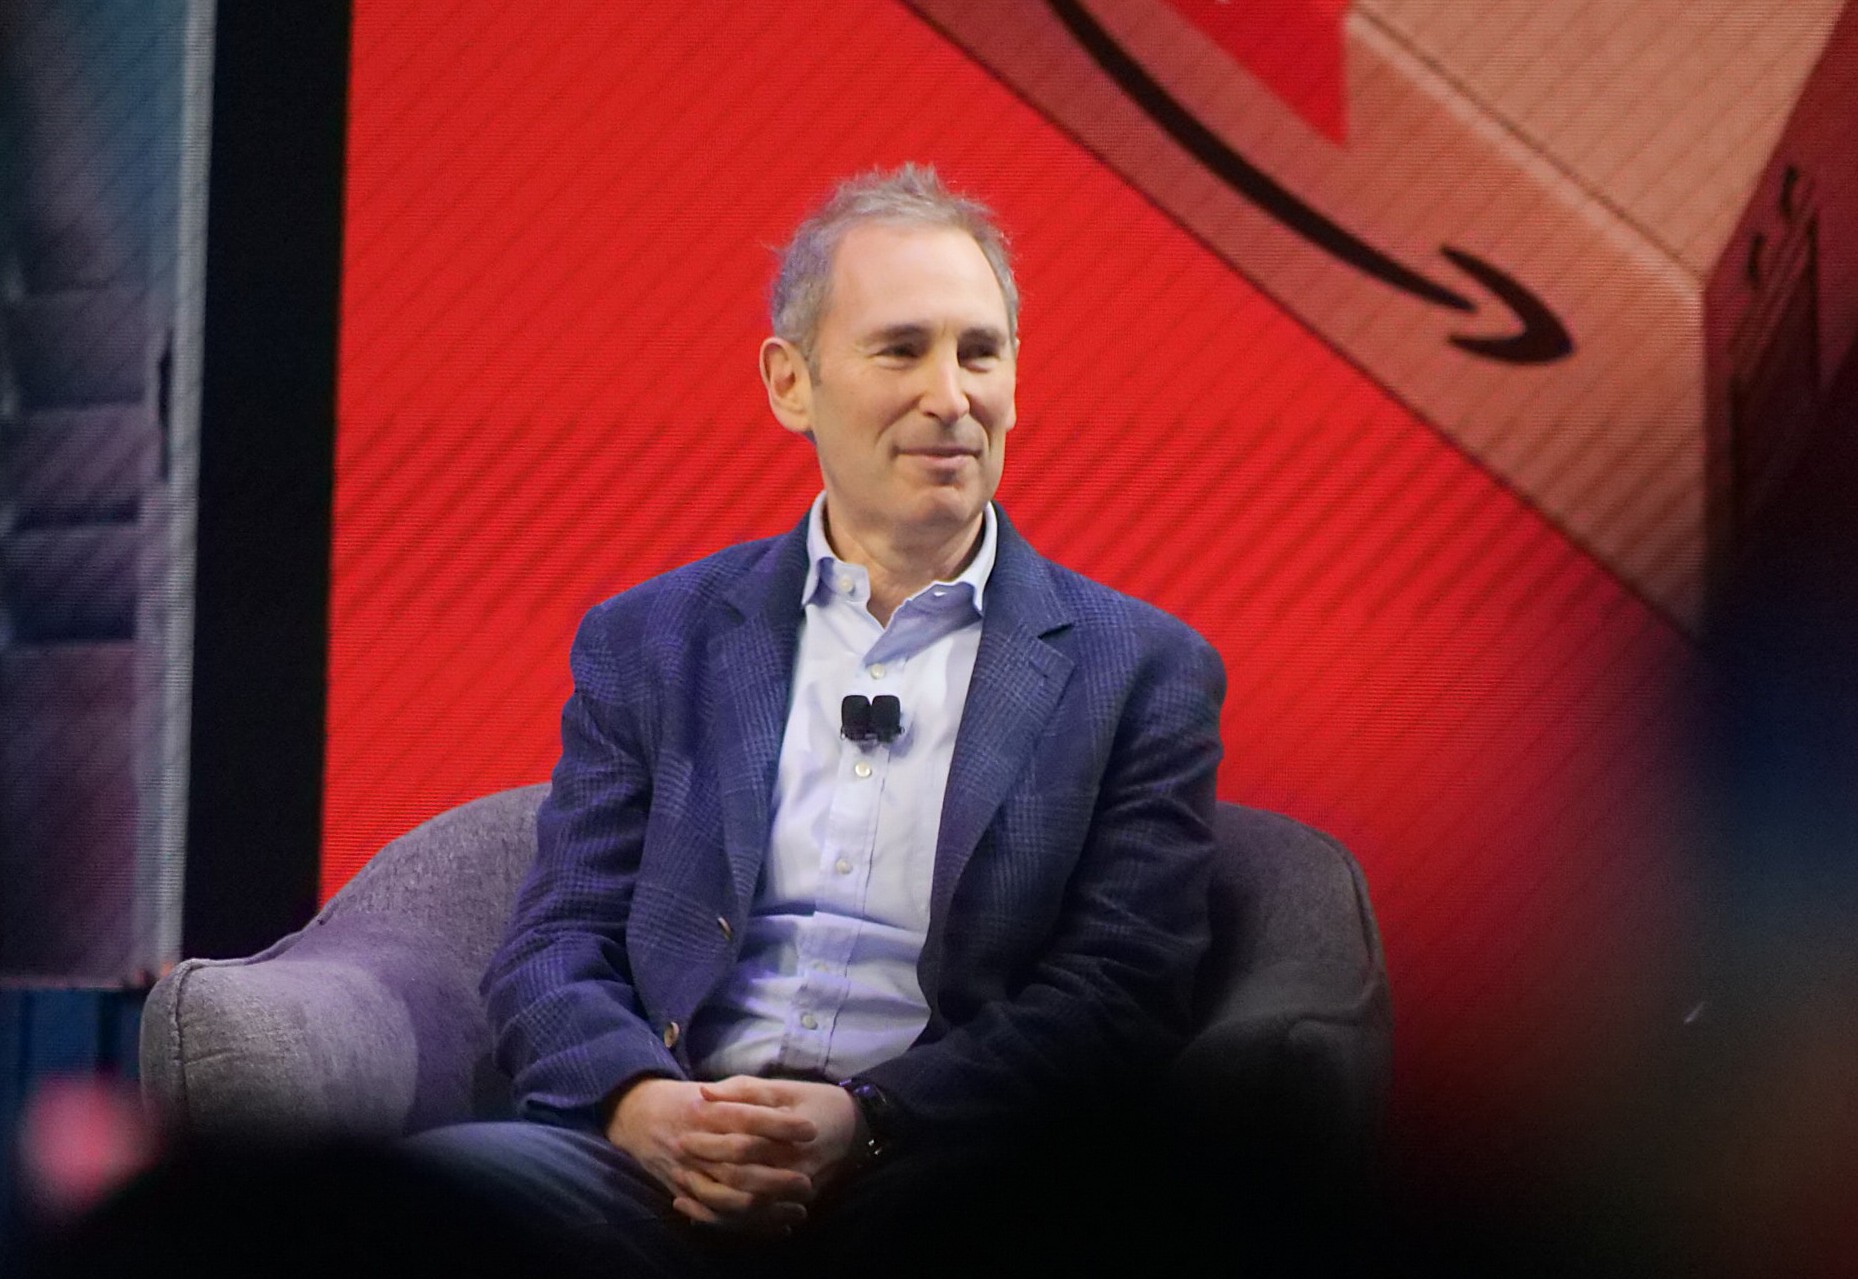
If you’ve been following the world of big tech, you know that Amazon has become something of a juggernaut in the cloud computing space, and right now it’s facing a strange but enviable problem: it simply can’t build data centers fast enough to satisfy the hunger for artificial intelligence. When Andy Jassy, Amazon’s CEO, sat down for a podcast with Andreessen Horowitz recently, he didn’t sugarcoat the situation. He basically said that Amazon could pour even more money into AI infrastructure and it would still be a smart investment, because the demand is so enormous. That’s a remarkable thing to hear from a company that’s already planning to spend around $220 billion this year on capital expenditures, mostly on AI and cloud capacity. To put that in perspective, Amazon originally planned to spend $200 billion, and it’s already raised that number substantially. Yet Jassy says the company is still leaving a meaningful amount of demand on the table. In other words, there are customers out there—especially AI labs like Anthropic and OpenAI, plus a growing number of traditional businesses moving to the cloud—who want more computing power than Amazon can give them right now. It’s a little like owning the only toll bridge in town and not having enough lanes to handle all the traffic. The good news for Amazon is that this is a high-quality problem to have. The tricky part is that it costs a fortune to expand, and that spending has consequences for the company’s bottom line, at least in the short term.
The spending spree is both a sign of confidence and a source of tension for investors. Amazon’s capital expenditures are enormous, and they’re only going to keep climbing if Jassy gets his way. He said on that podcast that AWS capacity is already largely booked up for this year and next, and even a good chunk of 2028 is spoken for. That kind of forward visibility is unusual and speaks to how locked-in many customers are, especially the big AI players. But building data centers, buying advanced chips, and wiring up massive server farms is incredibly expensive. In fact, over the twelve months ending in June, Amazon’s free cash flow was negative to the tune of $7.6 billion. That means the cash going out the door for infrastructure exceeded the cash coming in from operations. For a company that investors have long viewed as a cash machine, that’s a notable shift. But Jassy is not backing down. He’s essentially arguing that this is not wasteful spending; it’s the price of admission for owning the next wave of computing. And he’s probably right, because the AI boom is not slowing down. Every major tech company is racing to secure compute capacity, and Amazon wants to be the place where that compute lives. The risk, of course, is that if the AI bubble ever deflates or if demand levels off unexpectedly, Amazon could be left with a massive amount of unused infrastructure. But for now, Jassy and his team are betting that the smarter risk is doing too little, not too much. Wall Street will be watching Thursday afternoon when Amazon reports its third-quarter earnings, and the big question won’t be whether Amazon grew—it will be whether Amazon signals even more aggressive spending next year.
Let’s talk about the actual numbers, because they’re expected to be pretty solid, though the growth rate will look a bit slower than last quarter. Analysts are forecasting revenue of about $202 billion, which would be a 12% increase from the same time last year. That’s right at the top of Amazon’s own guidance, which ranged from $197 billion to $202 billion. On the earnings side, Wall Street expects around $1.96 per share, which is roughly flat compared to a year ago. But here’s the thing: the slowdown in revenue growth is partly a timing quirk, not a sign of weakness. Prime Day, Amazon’s biggest shopping event of the year, happened in the second quarter this year, whereas last year it fell in the third quarter. That shift creates a much tougher comparison for the current quarter. Amazon itself estimated that the timing change would shave nearly four percentage points off its growth rate. It hits the online store business hardest—analysts think that segment will only grow about 3% this quarter. That’s not exactly thrilling for a company that used to post double-digit growth in its core retail business like clockwork. But investors have largely gotten used to the idea that Amazon is no longer primarily a retail story. It’s a cloud and AI story, with retail as the steady, if unexciting, foundation. The real action is in Amazon Web Services, or AWS, which is the engine that generates most of Amazon’s operating profit. And that’s where things get interesting.
AWS is the crown jewel, and it’s been accelerating nicely. In the second quarter, AWS revenue grew 37% to $42.2 billion, which was its fastest pace since 2021 and the fifth straight quarter of accelerating growth. For the third quarter, analysts expect something similar: about $45.4 billion in revenue, up 37.5% from a year earlier. Some analysts, like the ones at Wedbush, are even more optimistic, projecting growth of around 41%. The reason for this optimism is that AWS has an enormous backlog of signed contracts that it hasn’t yet fulfilled. As of June, AWS had $496 billion in committed contracts, more than double what it had a year earlier. That’s a staggering number, and it essentially tells you that the company’s growth is no longer constrained by demand. It’s constrained by capacity—how fast Amazon can build new data centers, install racks of servers, and get them connected to the power grid. As one analyst put it, “Capacity, not demand, is the constraint.” That’s a nice position to be in, but it also means Amazon has to move with incredible speed. The company is also trying to make AI cheaper and more accessible. Jassy noted on that podcast that running AI models is still “an order of magnitude too expensive” for widespread business use. To fix that, Amazon has developed its own custom chips, including the Trainium AI processors, which are designed to do the heavy lifting for AI training and inference at a lower cost than Nvidia’s expensive GPUs. Amazon has said its chip business is on pace to generate more than $25 billion in annual revenue, which would make it a significant business in its own right. If Amazon can deliver that kind of performance, it could help bring down the cost of AI and make the technology more practical for everyday enterprises.
One of the most fascinating subplots in this earnings report is Amazon’s relationship with Anthropic, the AI company that makes the Claude models. Amazon has invested heavily in Anthropic, and that investment has made Amazon’s earnings extremely volatile. Last quarter, for example, Amazon reported $53.4 billion in pre-tax gains, mostly from the value of its Anthropic stake, which pushed earnings to $5.75 per share against expectations of just $1.82. That’s a huge swing, and it means that Amazon’s reported profit can look wildly different from one quarter to the next, depending on how Anthropic’s valuation moves. Anthropic recently filed paperwork for an initial public offering on the Nasdaq, which will be a major event for the AI industry. As of June 30, Amazon’s stake in Anthropic was valued at about $190 billion, according to Amazon’s latest quarterly filing. That includes about $92 billion in unrealized gains on convertible notes—a type of loan that converts into stock when Anthropic goes public. When that IPO happens, those gains will become real, and Amazon’s investment will likely be one of the most profitable bets in tech history. But the relationship is not just about financial gains. Anthropic is also one of Amazon’s biggest cloud customers. Its IPO filing shows commitments to spend at least $110 billion on Amazon’s computing capacity into the 2030s. That’s a staggering commitment, though interestingly, it’s slightly less than the $114.5 billion Anthropic has committed to Google. Anthropic also mentioned in its filing that it has asked its cloud providers for more computing power than they were willing to supply, which reinforces the broader theme that AI companies are desperate for infrastructure. For Amazon, having a close partnership with Anthropic is a double win: it makes money as an investor, and it makes money as a cloud provider. But it also creates some awkward dynamics, since Amazon’s own AI models, like the ones it sells through its Bedrock service, compete with Anthropic’s Claude. Still, the financial upside is so huge that Amazon is happy to play both roles.
Finally, there’s the emerging battle over the future of online shopping, which could threaten Amazon’s advertising business. Amazon recently blocked Meta’s new AI shopping agent, called Muse, from its platform, saying that the agent broke its rule requiring bots to identify themselves. This might sound like a minor technicality, but it’s actually a major strategic move. If AI agents are allowed to shop on behalf of customers, they could bypass the very thing that makes Amazon’s advertising business so lucrative: people browsing its pages and seeing ads. Amazon’s ad revenue grew 26% to $19.8 billion last quarter, and analysts expect about $20.8 billion this time, up 18%. That’s a big, fast-growing business, and Amazon doesn’t want software agents to cut it off. Some analysts, like those at Wedbush, see limited risk for now, arguing that Amazon’s logistics advantages and its role connecting shoppers with sellers will protect it. But Amazon is not taking chances. It’s been expanding its selection of products available on other retailers’ sites—about 250 million products now, roughly 2.5 times as many as in March. That’s a way to keep shoppers and sellers within Amazon’s ecosystem, even when they start their searches elsewhere. On the seller side, Amazon has also opened its tools to outside AI agents, starting with Anthropic’s Claude, which means it’s trying to shape the future of agentic commerce rather than fight it blindly. And all of this is happening as rivals Microsoft and Alphabet are reporting their own quarterly results, with Microsoft breaking out Azure revenue every quarter under a new structure. The cloud wars are heating up, and AI is the battlefield. For Amazon, Thursday’s earnings report will be more than just a check on the numbers—it will be a signal of how the company plans to navigate a world where AI is reshaping everything from infrastructure to shopping to the very nature of software. It’s a lot to digest, but one thing is clear: Amazon is all in, and Jassy doesn’t see a reason to slow down.