

White House Defends ‘Unprecedented’ Trump Crypto Ethics Pledges as Policy Drive Shifts to SEC
A New Front in the Digital-Asset Ethics Fight
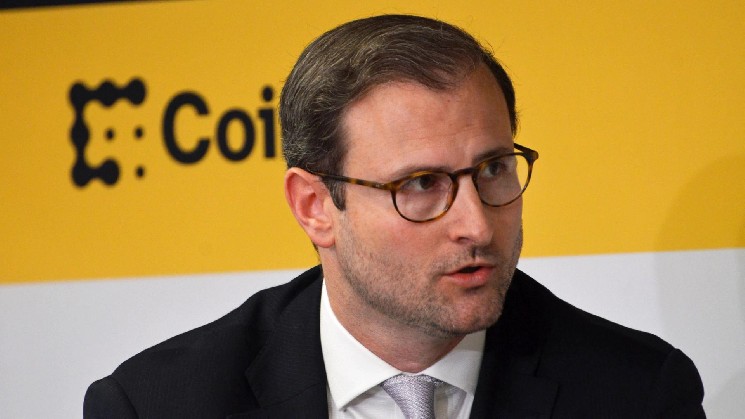
The White House is mounting an assertive defense against accusations that President Trump’s cryptocurrency holdings represent an intolerable conflict of interest, with a senior official insisting that the administration voluntarily embraced the most expansive ethical restrictions ever accepted by a sitting president. Speaking Tuesday at a CoinDesk Policy & Regulation event that drew some of the most influential figures in digital-asset policy, Witt — a principal architect of the administration’s crypto legislative agenda — sought to turn the tables on critics who have questioned whether the president’s personal financial empire is improperly influencing federal regulation. On the surface, the appearance was routine: a policy aide discussing pending legislation and regulatory priorities. Beneath the surface, however, Witt’s remarks served as a pointed counteroffensive against a narrative that has shadowed the White House since the president took office. “The president agreed to not one but two different ethics provisions that were unprecedented in nature,” he said. That framing is central to how the administration wants this conflict to be understood — not as a president circling his own business interests but as a leader who accepted constraints that no predecessor would have entertained. At stake in this rhetorical battle is more than political optics. The administration’s entire digital-asset agenda — a far-reaching platform encompassing stablecoin regulation, market-structure reform and even the integration of digital assets into the nation’s financial infrastructure — depends on the credibility of its claim to be acting in good faith. If the accusation of self-dealing sticks, every subsequent regulatory action becomes suspect. If it is defused, the White House gains breathing room to pursue an ambitious agenda largely favorable to the industry. The episode also underscores how the modern presidency has evolved into a tangle of personal wealth and public power — and how quickly that tangle can become a political liability.
Two Provisions With No Precedent
Expanding on that defense, Witt detailed the two measures that, in his estimation, lifted the president’s ethical obligations into entirely new territory. The first would have required Trump to divest his crypto holdings altogether or deposit them into a blind trust, an arrangement designed to sever any practical connection between the president and the assets he controls. The second provision was still more extraordinary, Witt said: it would have permitted state attorneys general to initiate legal action against the federal government should it fail to police ethical lapses internally. This, he argued, effectively creates an external enforcement mechanism — a layer of accountability that transforms ethics oversight from a self-policing enterprise into a federalism-based check on presidential power. “That is without a doubt the most unprecedented, far-reaching, stringent, restrictive ethics provision that has ever been agreed to by any president,” Witt said. “Far-reaching” is a precise word choice, suggesting a framework extending not merely to the president’s own finances but to the broader conduct of the executive branch. Even seasoned observers of presidential ethics were struck by the novelty of the arrangement. Historically, presidents have resisted even modest intrusions on their financial privacy, and the notion of inviting state-level prosecutors into the federal ethics arena runs against the grain of executive-branch tradition. That the White House would voluntarily embrace such mechanisms — and then advertise them publicly — indicates how acutely the administration feels the political temperature. Yet, for all their scope, the provisions were not enacted into permanent law; they remain a set of commitments, subject to interpretation, and entirely dependent on the goodwill of those doing the interpreting. Whether they would hold up under sustained legal challenge is an open question. Presidents from both parties have traditionally taken the path of least resistance when it comes to financial disclosure, relying on vague norms of recusal and avoidance rather than binding, enforceable constraints. In that light, the White House’s approach is genuinely different — and it is precisely that difference that makes it so politically awkward to attack.
The Ironic Counterpunch
Witt’s response to the Democrats leading the charge against the president did not rest on legalistic argument alone. He chose, instead, to meet the attack with a twist of his own. The allegation that Trump had an improper conflict in steering digital-assets policy while maintaining a sprawling crypto empire, he argued, was “somewhat ironic, given that we’re dealing with a lot of senators on banking committees who hold stocks and actively trade stocks in financial services companies that they regulate.” The implication was unmistakable: the very lawmakers calling for accountability are themselves entangled in the industries they oversee, exposed to the same species of conflict they now condemn. Witt’s comment revived a familiar and highly sensitive topic in Washington — the ethics of congressional stock trading. Over the past several Congresses, calls to ban members of Congress from owning or trading individual securities have gathered momentum, fueled by investigative reports revealing substantial trading activity among lawmakers with access to sensitive information. The ethical rules governing the legislative branch have remained essentially unchanged for decades, despite repeated scandals. Yet the practice persists, and the senators Witt singled out hold seats that place them in a direct regulatory relationship with the banks whose shares they trade. By raising this, Witt framed the debate in a way that is difficult to answer cleanly: if the ethics standard is actual or potential financial influence, then Congress itself is swimming in conflicts, many of them far less constrained than the ones the president accepted. It was a rhetorical strategy designed not merely to deflect but to expose — a reminder that in Washington, glass houses are the default form of architecture. Whether his jab moves the needle among independent voters remains to be seen, but it has already sharpened the terms of the public debate.
The Clarity Act: A Legislative Casualty?
Beyond the ethics skirmish, however, lies the legislative battle that Witt was originally hired to win. His primary role has been to shepherd the Clarity Act — a landmark measure intended to establish a coherent federal framework for digital assets — through Congress. For an industry that has long derided the uncertainty of piecemeal regulation, the bill represents a potential turning point, a chance to codify which tokens are securities, which are commodities, and which agencies hold the power to decide. Last week, that goal suffered a serious setback when the U.S. Senate declined to advance the legislation. The defeat was not entirely unexpected — crypto market-structure bills have historically struggled to build momentum — but it nevertheless landed with a thud among advocates who had believed the political winds were finally at their backs. The Senate’s failure laid bare a deeper reality: despite years of industry lobbying and a more favorable political climate in Washington, digital-asset legislation remains a heavy lift. Concerns about consumer protection, financial stability and the possibility of facilitating illicit finance continue to cool the enthusiasm of moderates in both parties. For the industry’s supporters, however, the vote was not merely a procedural loss; it was a wasted opportunity at a time when the United States is competing with jurisdictions such as the European Union and Singapore to set global standards for the crypto economy. The Clarity Act’s future is now uncertain, and with every passing month of inaction, the cost of regulatory ambiguity grows. That cost is paid not only by exchanges and developers but by ordinary investors who cannot predict whether a given token will be treated as a security or a commodity — and who thus face a minefield of conflicting rules and enforcement actions.
Turning to the SEC
If the legislative path appears blocked, the administration is making clear that it does not intend to wait. Speaking at the same event, Witt all but confirmed that the so-called lame-duck session at the end of this year is not a significant focus for his team, signaling that the odds of reviving the Clarity Act before year-end are slim. Instead, he said, the core work now is shifting to the federal regulators — in particular, the Securities and Exchange Commission. This pivot is significant. The SEC, through its enforcement priorities and interpretive guidance, has effectively been setting crypto policy by default, and its influence over the industry’s direction will only grow in the absence of a statutory framework. For an administration eager to deliver concrete outcomes, rule-making and enforcement provide a more reliable channel than an unpredictable Congress. But the shift is not without costs. Agency-driven policy is inherently more fragile than legislation; what one administration constructs through guidance, another can dismantle with a stroke of a pen. Moreover, the SEC’s cautious, case-by-case approach reads as agonizingly slow for an industry that moves at the speed of software. For market participants, the message is unambiguous: pay attention to the agency, not just the Capitol. The next chapter of crypto policy in the United States will be written in the Federal Register, in enforcement actions, and in the fine print of regulatory filings. For a White House eager to claim victories, the SEC offers a venue where progress can be measured in concrete actions rather than in floor votes.
High Stakes and an Uncertain Road Ahead
Taken together, these developments paint a picture of an administration defending its ethical credentials on one front, conceding defeat on the legislative front, and repositioning for a regulatory fight on a third. The SEC’s posture in the coming months will shape the day-to-day reality of cryptocurrency markets, determining everything from which tokens survive the compliance gauntlet to whether American innovation continues at home or migrates toward more permissive shores. On the ethics front, the controversy shows no signs of cooling. Witt’s arguments, however powerful rhetorically, are unlikely to satisfy Democrats who view the president’s crypto empire as a structural conflict that no ethical agreement can fully dissolve. For the administration, the story it tells is one of unprecedented restraint: two provisions, one divestiture or blind trust, and an extraordinary concession to state attorneys general. For the critics, the story is one of an industry reshaping the rules while its most prominent patron occupies the White House. As the year draws to a close, the Senate may yet contemplate a second attempt to revive the Clarity Act; the SEC will continue to shape policy through its docket, and state law enforcement officials will weigh whether to test the limits of their newly asserted authority. What is no longer in question is that digital-asset policy and presidential ethics have become permanently interlocked — and that the outcome of this year’s battles will determine the regulatory landscape for a generation. Global competitors are watching closely, and the United States must decide whether it wants to lead the digital-asset revolution or cede the field to more nimble jurisdictions.