

Crypto Economy Shows Remarkable Staying Power as $2.1 Trillion in Market Value Disappears
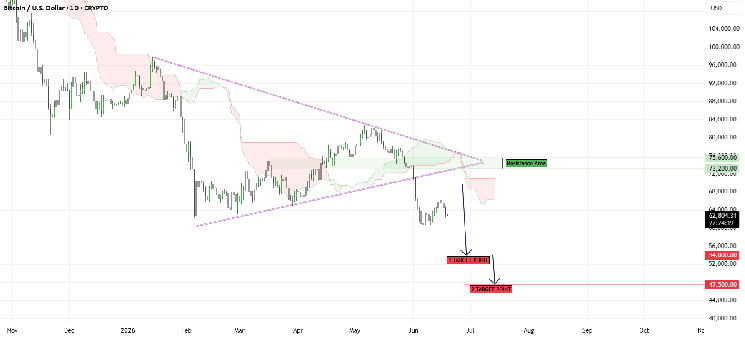
The past twelve months were, by virtually any measure, a brutal stretch for digital asset prices. The red dominated trading screens, sentiment turned sour, and the broader crypto market shed roughly $2.1 trillion in capitalization. The story that emerged from those headlines was predictable: a bubble deflating, interest fading, the industry retreating again. But a closer look at what actually happened underneath the price chaos tells a very different and far more interesting story. According to Chainalysis, the blockchain analytics firm, measured global crypto economic activity declined just 1.6% during the 12 months ended June 30, 2026. Total activity fell from roughly $9.5 trillion to $9.4 trillion. That is barely a blip. The stark gap between a market capitalization that collapsed and an economy that did not is not just a statistical curiosity. It is a sign that digital assets have moved into a new phase. The network is being used more like financial infrastructure and less like a speculative gamble. Prices, it turns out, can crash while the underlying rails continue to carry payments, transfers, savings, and settlement traffic across the world. For anyone following crypto closely, that changes the way the current downturn should be understood.
To understand why this matters, it is important to be precise about what the Chainalysis 2026 Global Crypto Adoption Index actually measures. The index is not a survey or a sentiment poll. It is based on transaction activity across the world’s major blockchain networks, including Bitcoin, Ethereum, stablecoin platforms, and a wide range of other digital asset ecosystems. The figure attempts to capture the real volume of economic value moving through those networks, whether in the form of peer-to-peer transfers, payments for goods and services, stablecoin settlements, or flows routed through centralized exchanges and custodial services. This is a fundamentally different dataset from market capitalization. A market cap tells you what an asset is worth at any given moment, but it tells you nothing about how often that asset is being used. A stock can fall dramatically in value while the company behind it is still hiring, producing, and generating revenue. The same logic applies to crypto. The fact that global crypto economic activity only dipped by 1.6% while prices were in freefall suggests that the usage side of digital assets has become far more resilient than the speculative side. It also suggests that when people talk about crypto being dead, they are looking at the wrong number. The price chart is easily visible; the transaction chart is quieter, but it has been moving steadily along.
Perhaps the most striking evidence of this resilience is where the growth occurred. Chainalysis found that domestic peer-to-peer crypto transfers, which involve individuals sending money directly to each other rather than through an exchange or broker, rose by 302.9% to $228.7 billion during the same period. Cross-border stablecoin flows climbed 77.5% to $220.3 billion. Those are enormous increases, and they point to a clear pattern: crypto is transforming into a real-world payments infrastructure. In countries with unstable currencies, expensive banking systems, or limited access to traditional financial services, a digital dollar token has immense practical value. It can hold savings when the local currency is losing value, facilitate cross-border business payments without the cost and delay of correspondent banking, and allow family members in different countries to transfer money without relying on outdated remittance systems. The same report found that the value moving into centralized crypto services, meaning exchanges and custodial platforms that dominate trading volumes, declined 4.3%. That makes the overall picture even more telling. The speculative trading side of the market cooled down, but the utility side accelerated. People are no longer just buying crypto because they expect the price to skyrocket. Many are using it because it solves an everyday problem, such as moving money across a border or preserving wealth in an inflationary environment.
This distinction is even more important when compared with earlier crypto cycles. In previous downturns, the collapse in prices usually carried activity down with it. When speculative enthusiasm died, so did the usage metrics. In 2018, the market lost a substantial portion of its value and the ecosystem went quiet for months. In 2022, after a series of high-profile failures, on-chain activity slowed dramatically as well. The trend was consistent: a bear market meant a shrinking network, not just lower prices. This time, the relationship appears to have broken. Stablecoins are the main reason. A dollar-backed token does not rely on appreciation to be useful. Whether Bitcoin is setting records or stuck in a prolonged drawdown, a stablecoin can still be used to pay a supplier, move savings out of a collapsing currency, or settle a transaction in seconds rather than days. The current data suggests that a growing number of people and businesses are using crypto the same way they would use a bank account, not a lottery ticket. That is a fundamental shift. It means the network no longer goes quiet when the market turns red. Instead, it simply shifts toward more practical, less speculative uses. For a technology that has often been dismissed as a casino, that is a meaningful measure of maturity.
None of this should be read as downplaying the pain of the current cycle. A $2.1 trillion loss in market capitalization is an enormous destruction of paper wealth. It has hurt investors, pressured companies, and led to significant job losses across the digital asset industry. Venture funding has pulled back, expansion plans have been shelved, and many projects that depended on a favorable market environment have disappeared. The 4.3% decline in value flowing to centralized services also suggests that the trading sector is still vulnerable to the mood of the market. The central finding of the Chainalysis report is not that the bear market was painless. It is that the economy underneath the bear market did not shut down. A 1.6% decline in global crypto economic activity, set against a market that lost trillions in value, is close to a flat line. That is a genuinely important signal for regulators, policymakers, and institutional investors. It shows that the sector has become less dependent on constant price appreciation and more grounded in tangible use cases. It also reinforces a distinction that dominates in traditional finance but has often been missing in crypto debates: the value of an asset and the utility of a network are not the same thing. They can diverge, sometimes dramatically.
The real lesson from the 2026 Global Crypto Adoption Index is not that crypto has become immune to bear markets. It has not, and it probably never will be. Prices can still crash, confidence can still erode, and wealth can still evaporate. But what has changed is that the stage on which those price movements occur now has a life of its own. More people are using stablecoins for cross-border payments. More people are turning to peer-to-peer transfers in markets where the traditional banking system is too expensive, too slow, or too fragile. More businesses are discovering that digital asset rails can move money more efficiently than the legacy infrastructure, regardless of what analysts think about the price of Bitcoin. The slow but steady decline in centralized service flows is a reminder that crypto still has work to do in rebuilding trust and demonstrating value to the mainstream. But the growth in stablecoin activity and P2P transfers points directly to the future. The crypto industry has often been defined by its most vocal evangelists and its most spectacular collapses. This report offers a different lens. It shows that the underlying technology is becoming part of the global economic fabric in ways that do not always make headlines. The price chart tells you what crypto is worth. The transaction data tells you what crypto does. And in a year when prices went off a cliff, what crypto did remained remarkably consistent.