

If you’ve opened your homeowners insurance renewal lately and felt your stomach drop, you’re not alone. Across the country, millions of people are paying significantly more to protect the places where they live, raise their families, and store their memories. A new analysis from NerdWallet, based on more than 840 million home insurance rate estimates from Quadrant Information Services, paints a vivid and somewhat unsettling picture: the typical American homeowner’s premium has jumped 24 percent in just three years. In early 2023, the median annual premium for a home with $300,000, $400,000, or $500,000 in dwelling coverage was $2,068. By early 2024, it had climbed to $2,212. By early 2025, it reached $2,452. And by early 2026, it hit $2,564. That’s an extra $496 per year for the same house, the same coverage, and, in many cases, the same insurer. For a family already stretching to pay for groceries, gas, and school supplies, an extra $40 a month is not pocket change. It’s a real squeeze. And when you consider that these numbers represent the typical homeowner—someone with good credit, no claims, and a house built in 1984—you begin to understand just how broad and deep this insurance crunch has become. It’s not something happening only to people in coastal mansions or wildfire zones. It’s happening in ordinary neighborhoods, to ordinary people, from small towns to big cities. The question on many minds is simple: why? And, perhaps more importantly, is there any relief in sight?
The national numbers tell only part of the story, because pain is not evenly distributed across the map. While every region of the United States saw premiums rise over the past three years, some areas were hit far harder than others. The Midwest, for instance, experienced the steepest overall climb, with coverage costs rising about 25 percent from the first quarter of 2023 to the first quarter of 2026. That may not sound dramatic until you put it next to other parts of the country: the Northeast saw premiums rise 20.5 percent, the South 19.2 percent, and the West 16.4 percent. Think about what that means for a family in, say, Wisconsin or Michigan. Their insurance bill is not just creeping upward; it’s leaping. NerdWallet found that Wisconsin homeowners endured a jaw-dropping cumulative premium increase of 40.9 percent over those three years—far above the national average. Michigan wasn’t far behind at 29.9 percent, followed by Iowa at 27.7 percent, Minnesota at 27.3 percent, and Indiana at 27.2 percent. To put that in human terms, a homeowner in Wisconsin who paid $2,000 for insurance in 2023 might now be paying closer to $2,818. That’s a serious hit to any household budget, especially in a region where winters are already expensive and summer storms can bring sudden, costly damage. It’s easy to assume that the biggest insurance problems are reserved for hurricane coasts or wildfire-prone hills, but the data tells a different, more complicated story. The Midwest has become an insurance hot spot, and residents there are feeling the consequences every time they pay their mortgage escrow or write a check to their insurer.
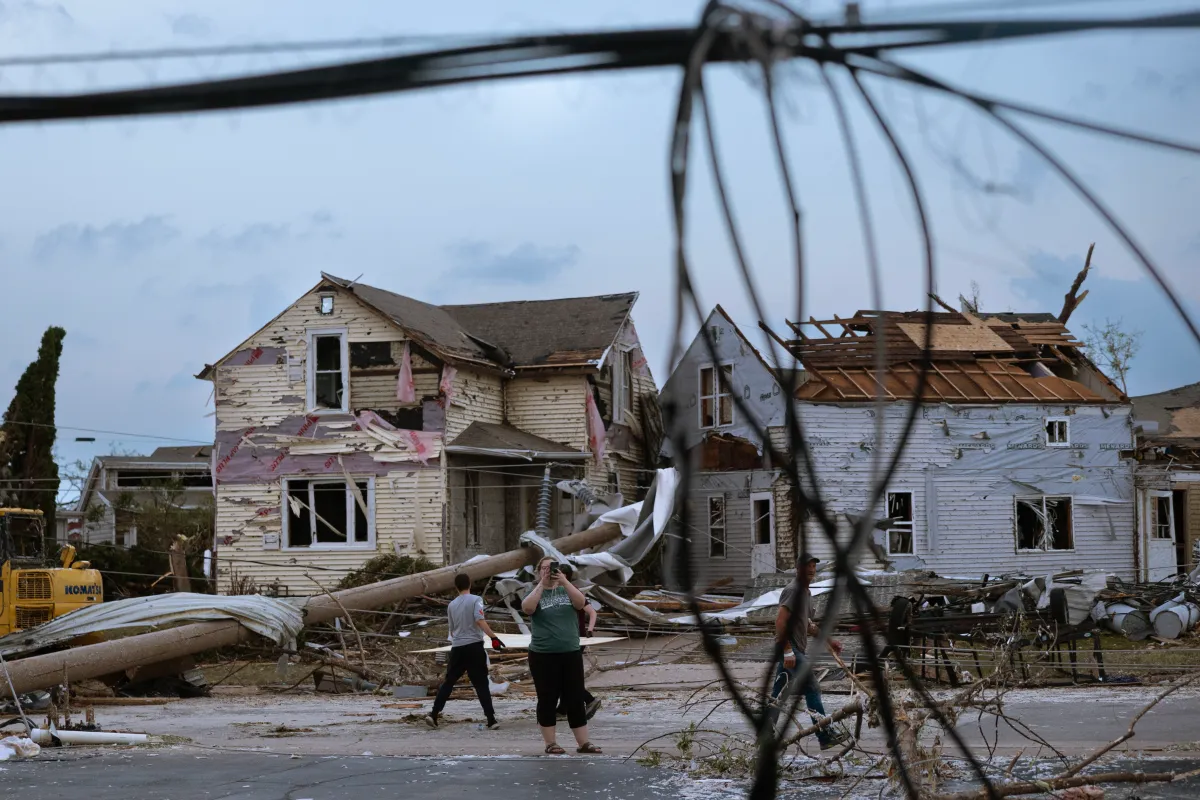
So why has the Midwest been hit so hard? The answer, according to the data, is written in the sky. Over the past several years, the region has been pummeled by extreme weather events, particularly tornadoes and hail. And while severe weather has always been part of life in the Plains and Great Lakes states, the frequency and intensity of these events have escalated in ways that are hard to ignore. NerdWallet’s analysis of National Oceanic and Atmospheric Administration (NOAA) storm data from 2020 to 2025 found that three of the four U.S. states with the largest cumulative increases in severe hail events since 2023 are in the Midwest. Severe hail, defined as hail measuring at least one inch in diameter, can shred roofs, dent siding, shatter windows, and ruin cars. In Missouri, severe hail events jumped by a stunning 276 percent when comparing 2023 through 2025 to the previous three-year period. In Illinois, they rose 258 percent. In Indiana, they climbed 183 percent. For homeowners, these numbers translate into more claims, higher repair costs, and, ultimately, bigger premiums. Insurers are not in the business of absorbing losses silently; they price risk based on the likelihood of damage. When a state starts seeing hailstorms that are nearly four times more frequent than before, actuaries take notice. They raise rates to make sure they can cover the expected costs, and those increases are passed along to policyholders. It’s a cold calculus, but it’s also a very human one. When your neighbor’s roof gets replaced after a storm, the cost of that replacement doesn’t just disappear—it gets folded into the broader pool of risk that everyone in the state shares. The result is that even homeowners who were lucky enough to escape the hail damage still end up paying for the storms that hit their communities.
There is, however, a small glimmer of hope buried in the data. While premiums have continued to rise over the past year, the pace of that growth has slowed significantly, offering a possible sign that the worst of the insurance shock might be easing. Between early 2023 and early 2024, premiums nationwide rose by 7 percent. Between early 2024 and early 2025, they rose by a much sharper 10.8 percent. But between early 2025 and early 2026, the increase dropped to a more modest 4.6 percent. That’s still an increase, and for anyone living on a fixed income or in an already tight budget, any increase matters. But it’s a noticeable slowdown, and in some places, prices actually went down. Over the past year, premiums fell in 18 states and Washington, D.C. That’s a dramatic change from the previous two years, when only three states saw declines in each year. For example, Alaska, New Mexico, and West Virginia saw premiums fall between 2023 and 2024, while Florida, Nevada, and Wyoming saw reductions between 2024 and 2025. The most impressive recent declines were in North Carolina, where premiums dropped 9.6 percent, Rhode Island at 7.9 percent, and West Virginia at 7.6 percent. To hear that your insurance bill might shrink rather than grow is genuinely encouraging. Part of this slowdown can be attributed to a relatively calm Atlantic hurricane season in 2025, which meant insurers didn’t have to pay out billions in coastal claims. Regulatory reforms in California and Florida also appear to have helped stabilize some of the most troubled markets in the country. Still, it would be a mistake to assume that the hard part is over. Even as national growth slows, four states reported double-digit increases over the past year, led by Pennsylvania at 16.4 percent, Arizona at 14.9 percent, and Minnesota at 10.9 percent. The picture is mixed, and while there’s reason to breathe a little easier, there’s also reason to keep your guard up.
One of the more complicated reasons behind the recent premium swings has to do with something called reinsurance, and understanding it can help homeowners make sense of what’s happening in their mailboxes. Reinsurance is essentially insurance for insurance companies. When a home insurer wants to protect itself against catastrophic losses—say, a massive tornado outbreak or a devastating wildfire—it buys its own coverage from large global reinsurers. Those policies are often renewed in January, and in early 2023, reinsurers delivered a brutal shock to the industry. Rates nationwide rose by 25 to 50 percent for insurers with a relatively clean record of recent losses, and by 45 to 100 percent for home insurers that had paid out large-dollar claims in the previous years. Private insurers, already wrestling with the higher costs of more frequent and severe storms, could not simply turn around and pass those higher reinsurance bills to consumers overnight. In many cases, they had to wait for regulatory approval to change their rates, which can take months. That delay means that the huge premium increases consumers saw in 2023 and 2024 were, in part, a delayed response to earlier reinsurance costs. By the time those increases worked through the system, reinsurance pricing had begun to stabilize, which helps explain why the most recent year’s premium growth has been more subdued. But this lag creates a lot of uncertainty for homeowners. Your renewal notice this year might reflect costs from two years ago, not what’s happening today. And if another catastrophic storm season hits, or if reinsurers decide to hike their prices again, the cycle could repeat itself. It’s a reminder that home insurance is not a simple product; it’s tied to a vast, interconnected global financial system. When someone on the other side of the world invests in catastrophic risk, or when a reinsurer in London or Zurich raises prices, it can eventually show up in the bill of a homeowner in Ohio or Iowa.
So what should a homeowner actually do with all this information? First, it’s worth remembering that insurance is meant to be a safety net, not a savings account. The goal isn’t to get the cheapest policy possible; it’s to find a policy that genuinely protects you when something goes wrong. That said, you don’t have to accept rate increases without question. One of the most practical steps is to shop around. NerdWallet’s analysis shows that insurers’ filed rate formulas vary widely, and different companies can offer very different prices for the same home. Getting quotes from multiple insurers can uncover significant savings, especially if you’ve been with the same carrier for years and haven’t recently reviewed your options. It’s also worth asking your current insurer about discounts. Bundling home and auto policies, installing storm-resistant roofing, adding smart water leak detectors, improving your home’s electrical or plumbing systems, and having a good credit score can all lower your premium. Another option is to revisit your deductible. A higher deductible can reduce your annual premium, but only if you can comfortably afford the out-of-pocket cost in the event of a claim. If you live in an area prone to hail or tornadoes, talk to a local contractor or insurance agent about ways to harden your home—things like impact-resistant shingles or reinforced garage doors can sometimes earn you credits. And if your premium has soared, don’t be afraid to challenge it. Ask your insurer to explain the increase. Look for errors in your home’s replacement cost estimate. Make sure they know about any renovations you’ve made that could lower your risk. At the end of the day, the insurance market is changing, and no single family can stop the broader trends of climate change and catastrophic weather. But that doesn’t mean you’re powerless. By staying informed, asking questions, and shopping smart, you can take some control back. The road ahead may still be bumpy—premiums are still rising in most states, and the future is impossible to predict with certainty. But for anyone who’s ever sat at the kitchen table, staring at an insurance bill and wondering how they’ll afford it, the first step is simply knowing that the problem isn’t invisible, it’s not personal, and there are ways to fight back. Home is worth protecting, and with a little effort, you can make sure that protecting it doesn’t cost more than you can bear.