




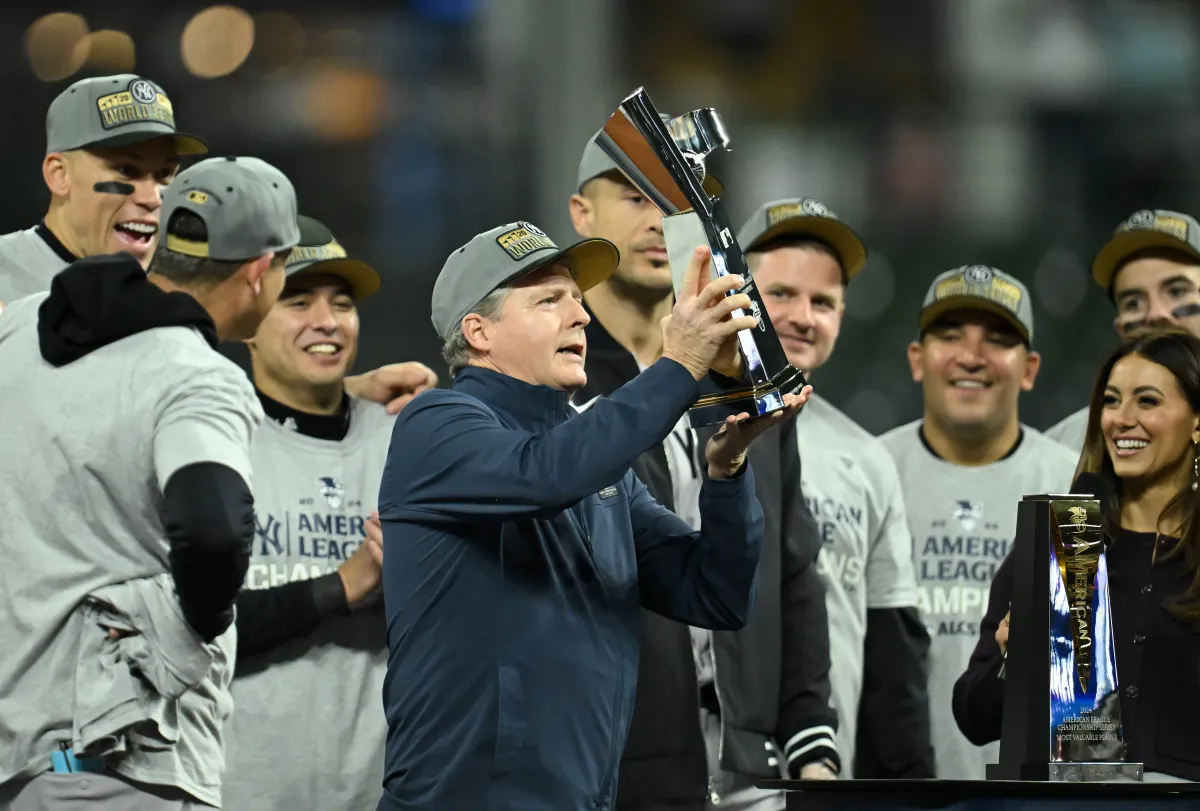
Major League Baseball has always been a sport with a stubborn fondness for the past. From the height of the mound to the sound of the umpire calling “Play ball,” baseball wraps itself in tradition. That is especially true when it comes to ownership. For more than a century, the people who controlled major league franchises were the sort of names you would expect to find on old stadium gates: family dynasties, self-made tycoons, oil heirs, beer barons, and media moguls. It was an exclusive club, and the league worked hard to keep it that way. There is a small but important rule in place that has long preserved this staid tradition: private equity firms were not allowed to own more than 15 percent of an individual franchise. That may sound like an arcane financial detail, but it was a powerful safeguard, a quiet way of saying that baseball teams should be owned by people, not funds, and that control should remain in familiar, patient hands. But last summer, according to Forbes’ Maury Brown, MLB quietly changed that rule to align itself more closely with the NBA, where the private equity limit is 20 percent. Nobody really noticed at first. Then a firm called Apollo Global Capital decided it wanted to buy more than 15 percent of a team, and not just any team. The team was the New York Yankees. Suddenly, the rule change wasn’t theoretical anymore. It was the opening act in the most valuable franchise transaction baseball has ever seen, a deal that cracks open the doors of the old boys’ club and invites Wall Street inside.
So what exactly happened? In August, the Wall Street Journal reported that Apollo Global Capital would pay $2.6 billion for a minority stake in Yankee Global Enterprises, the holding company that controls the Yankees. The New York Post later reported that the deal values the Yankees at more than $12 billion, the highest valuation ever placed on a baseball franchise. But the money doesn’t all arrive at once, and the structure is more nuanced than a simple check. According to multiple reports, Apollo is paying $800 million for an initial 8 percent stake in Yankee Global Enterprises, with an agreement to purchase another 8 percent over the next four years for an additional $800 million. That brings Apollo’s total ownership to 16 percent, just above the old MLB limit and still under the newly relaxed 20 percent ceiling. On top of that, Apollo is also lending the Yankees $1 billion. CNBC’s Mike Ozanian broke down the valuation on Monday, saying, “They’re going to get well, well above $12 billion.” It is a staggering number, especially when you consider that the Yankees are not just a baseball team but a global brand. Yankee Global Enterprises also holds stakes in Legends Hospitality, the YES Network, New York City FC, and even AC Milan. Apollo is not simply buying a piece of the pinstripes; it is buying into a diversified sports, media, and entertainment empire. And yet, the Steinbrenner family remains firmly in charge, holding on to a little more than 60 percent of the team. This is not a sale of the crown jewels. It is more like inviting a wealthy neighbor to help with the estate while keeping the keys to the castle.
Why would the Yankees, one of the most iconic and profitable franchises in sports, want to sell a piece of themselves to a private equity firm? And why would Apollo want in? The romantic answer might be that Apollo’s partners grew up dreaming of Yankee Stadium and wanted a piece of the legend. But the New York Post reported that the real motivation was far more practical, even a little mundane. The impetus for the deal was estate planning. A group of limited partners in Yankee Global Enterprises wanted to cash out their investments, likely to handle inheritance issues and pass wealth to the next generation without triggering a messy forced sale. Apollo, meanwhile, was looking for an anchor investment for its newly created sports fund. It needed a flagship deal, something big and safe and prestigious enough to attract other investors. The Yankees fit the bill perfectly. In other words, this wasn’t a hostile takeover or a desperate cash grab. It was a financial transaction between sophisticated players who saw an opportunity to solve each other’s problems. The limited partners get liquidity. Apollo gets a blue-chip asset with global name recognition and a steady stream of revenue. The Steinbrenners get capital to refinance debt, invest in the team, or expand their holdings. And Major League Baseball gets a new precedent. It is a reminder that even the most tradition-bound institutions eventually have to adapt to the times, especially when generational wealth is on the line.
The rule change itself may turn out to be more important than the Yankees deal. For years, MLB limited private equity ownership to 15 percent of any team, a deliberate barrier designed to keep hedge funds and investment firms from treating franchises like speculative assets. But by raising the limit to 20 percent, the league is signaling that it wants to make it easier for teams to raise capital without surrendering control. That is a significant philosophical shift. Private equity firms are no longer just silent minority partners; they can now hold a substantial slice of a franchise and, with it, a louder voice in how the team is run. How much interest the relaxed rules will generate remains an open question. Some teams may be reluctant to bring in outside investors, especially those with strong family ownership traditions. But the Yankees, of all teams, choosing to test the new limit sends a powerful message. If the most storied franchise in baseball is willing to sell 16 percent to Apollo, other owners are likely to pay attention. Teams might look at the deal and see a way to fund stadium renovations, invest in analytics and player development, or simply cash out some of their paper wealth while retaining control. For private equity firms, meanwhile, baseball teams have become increasingly attractive because they are scarce, iconic, and generally resilient investments. In a low-yield world, a piece of a franchise like the Yankees can seem like gold.
It is worth pausing to appreciate how much the business of baseball has changed. The Yankees are not just a team; they are a media and hospitality conglomerate wrapped in a sports uniform. Through Yankee Global Enterprises, the franchise is connected to Legends Hospitality, which runs concessions and premium services at stadiums across the country; the YES Network, which broadcasts games and generates enormous cable revenue; New York City FC, a Major League Soccer club; and AC Milan, one of the most famous soccer teams in Europe. When Apollo buys 16 percent of Yankee Global Enterprises, it is buying a piece of all of that, not just the 26 World Series trophies in the Bronx. That is why the valuation can reach $12 billion and why Ozanian believes the true number could climb even higher. The Yankees have become a globally diversified sports empire, and the Steinbrenners are behaving like the chief executives of a multinational corporation rather than the stewards of a beloved civic institution. That might sound cold, but it is also the reality of modern sports. Television contracts, streaming rights, international sponsorships, and real estate development have transformed teams into financial assets with balance sheets, debt obligations, and growth targets. The Apollo deal is just the latest sign that baseball has fully entered the era of financialization. It may not be what fans want to think about while sitting in the bleachers, but it is the engine that keeps the game running.
In the end, what does this mean for the future of baseball? On one hand, it could be a healthy development. Private equity money can provide teams with the resources they need to compete in an increasingly expensive sport, without forcing owners to sell the team outright. It can also give families an exit strategy without breaking up long-held ownership structures. On the other hand, there is something a little unsettling about private equity firms taking larger stakes in America’s pastime. These firms are not sentimental. They are built to generate returns for their investors, and they tend to measure success in quarterly numbers rather than pennants. The worry is that teams could become more focused on maximizing profits than on winning championships, or that decisions about payroll, ticket prices, and player development could be made with an eye toward short-term financial performance rather than long-term fan loyalty. But for now, at least, the Steinbrenners remain firmly in control, and Apollo appears to be a patient partner rather than an activist investor. The Yankees have always found ways to reinvent themselves, from the days of Babe Ruth to the era of Aaron Judge. This deal is another reinvention, a quiet but historic adjustment to the rules of ownership. Baseball has always been slow to change, but when it does, it usually makes a statement. The Apollo stake in the Yankees is that statement: the old boys’ club has opened its doors, and Wall Street is now sitting in the suite.