




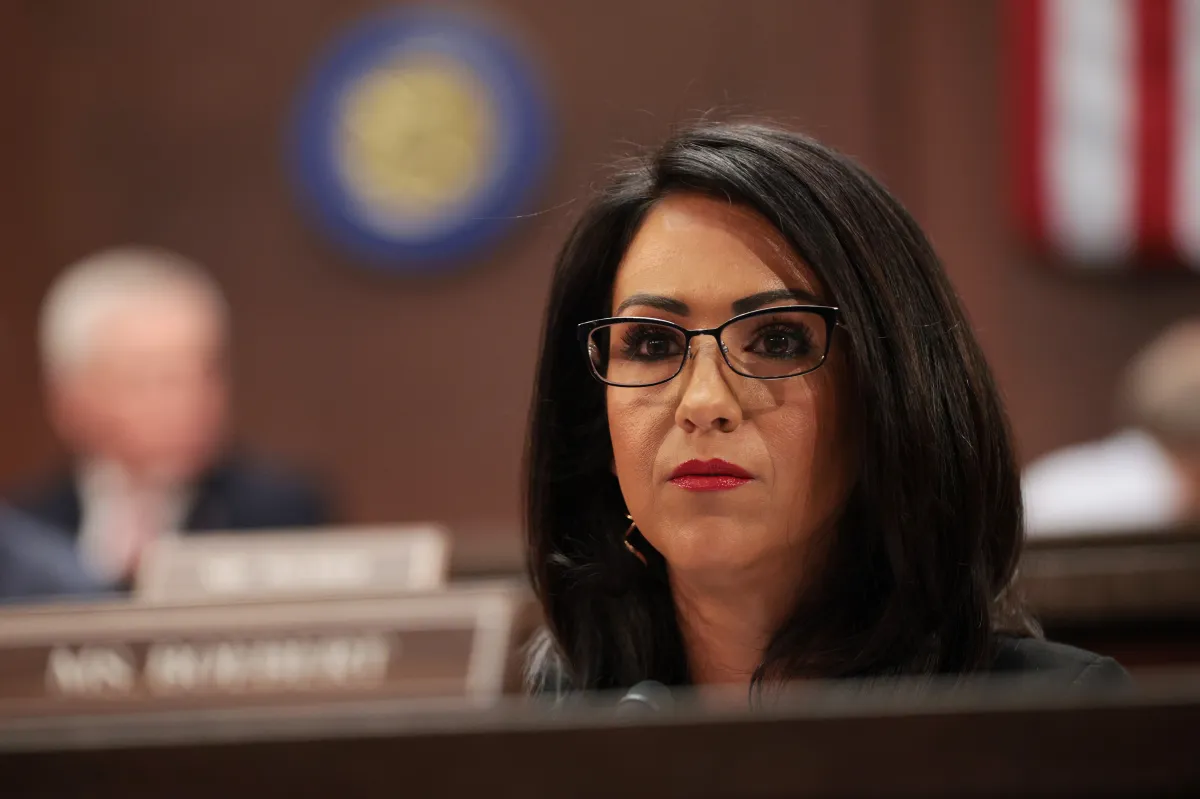
For many American families, homeownership has started to feel less like a dream and more like a locked door. That’s the frustration at the heart of Representative Lauren Boebert’s latest push, a call for a broad rethinking of how mortgage lending works in the United States. In a letter to senior Trump administration officials who oversee housing, finance, and agriculture policy, the Colorado Republican argued that the current system is leaving too many qualified people outside the gates of the housing market. The problem, as she frames it, is not just high prices or interest rates, though those matter enormously. It’s also the outdated and often rigid lending standards that decide who is allowed to borrow in the first place. “Affordability is what families talk about around the kitchen table in the heartland,” Boebert wrote, in a tone meant to reach beyond the halls of Congress. “Republicans in Congress cut taxes. Next, we need to reform the home-buying process.” The letter isn’t a bill yet, and it doesn’t change any rules on its own. But it signals a growing political push to make the mortgage system more responsive to how ordinary Americans actually live, work, and save. For Boebert, the goal is to modernize the path to ownership rather than simply lower the bar, though critics are already asking whether that distinction is as clear as it sounds.
The central complaint behind Boebert’s proposal is that traditional mortgage underwriting relies too heavily on a narrow set of financial signals, like conventional credit scores, long credit histories, and large cash reserves. That leaves many borrowers who are perfectly dependable in real life unable to prove it on paper. Boebert argues that lenders should be allowed, and perhaps encouraged, to look at broader evidence of financial responsibility. For example, an applicant who has paid rent on time for years, without ever missing a payment, could have that history considered as a mark in their favor. Similarly, people who earn income through seasonal work, commissions, freelance contracts, or their own small businesses are often penalized by underwriting systems designed for steady W-2 employees with predictable paychecks. In an economy where more and more work is irregular, contract-based, or entrepreneurial, that creates an unnecessary mismatch between creditworthiness and actual ability to pay. Boebert’s letter calls on federal housing and financial regulators to explore more flexible down-payment requirements for conventional and jumbo loans, to consider on-time rent payments when evaluating borrowers, and to develop alternative approaches to creditworthiness that go beyond the traditional credit score. She described many of the current requirements as “arbitrary barriers” that don’t make lending safer. They simply keep people renting longer. Financial educators and housing experts see both merit and risk in that argument. As Alex Beene, a financial literacy instructor at the University of Tennessee at Martin, put it, the housing market has a genuine tension: Americans can demonstrate for years that they reliably pay substantial rent and household bills, yet still struggle to qualify for a mortgage because traditional underwriting may not fully capture that financial history.
One of the most striking changes Boebert wants to revisit is the long-standing expectation that buyers put 20 percent down. That rule of thumb has been treated for generations as the gold standard of responsible borrowing, a way to ensure buyers have real skin in the game. But Boebert argues that the 20 percent requirement has become less about safety and more about exclusion. The math is stark. For an $833,000 jumbo mortgage, a 20 percent down payment would require roughly $167,000 in cash. Under a 5 percent down-payment model, the same purchase would require only about $42,000. That difference can mean years of additional renting, saving, and waiting for families who are otherwise ready to own a home. “Keeping the bar at 20 percent does not automatically make the loan safer,” Boebert wrote. “It just delays homeownership and keeps people renting longer.” That argument resonates with many younger buyers and middle-class families who have watched housing prices soar beyond the pace of wage growth. They may have solid incomes, steady employment, and a proven ability to pay a monthly mortgage, but the upfront cash hurdle can still be overwhelming. Boebert’s proposal does not suggest eliminating down payments altogether. Instead, it asks regulators and lenders to think more carefully about whether rigid requirements are protecting borrowers or simply freezing them out of the market. In that sense, her message is less about throwing caution to the wind and more about asking whether caution has become another word for indifference.
If Boebert’s proposed reforms were adopted, the beneficiaries would be an unusually broad cross-section of American households. Long-term renters would be at the top of the list, especially those with limited traditional credit histories but excellent payment records on rent and utilities. Farmers and ranchers, whose earnings naturally rise and fall with seasons, weather, and commodity prices, could also find it easier to prove their financial stability. Small-business owners and self-employed workers, who often have solid incomes but messy tax returns, could see more opportunities to qualify. And trades workers or commission-based employees, who may have strong years and lean years, would no longer be written off as unreliable simply because their paychecks don’t arrive in the same way every month. As Michael Ryan, a finance expert and founder of MichaelRyanMoney.com, told Newsweek, there are Americans who may be perfectly capable of making a mortgage payment but get screened out because the system doesn’t measure their creditworthiness particularly well. Looking at rent payment histories or newer credit models could be a smart move if it identifies responsible borrowers more accurately. But Ryan also sounded an important warning. If the house simply costs too much relative to a borrower’s income, lowering the financing hurdle doesn’t magically make the house cheaper. It may simply allow the borrower to take on more debt. That’s where the lesson of the 2008 financial crisis matters. Expanding responsible access to credit is not the same as solving housing affordability, and modernizing underwriting should never mean weakening the basic question lenders still have to answer: Can this person realistically pay this money back?
Opposition to Boebert’s ideas is already forming from both sides of the ideological spectrum. Some conservatives and housing market veterans argue that lower down-payment requirements increase the risk of default during economic downturns or housing market corrections. If a borrower has little of their own money invested at the start, the reasoning goes, they may be more likely to walk away when home values drop or when financial hardship hits. Kevin Thompson, CEO of 9i Capital Group and host of the 9innings podcast, invoked history directly. “Those who don’t know history are doomed to repeat it,” he told Newsweek. “I think we have been through this before, where we made it easier for people to purchase homes and eased access to loans, only to almost find ourselves in a financial crisis.” Economists are also divided over whether loosening lending standards would genuinely improve affordability or simply pour more fuel into an already overheated housing market. After all, if more people are suddenly able to qualify for mortgages, demand could rise even further, pushing prices even higher in a market already groaning under severe housing shortages. Still, Beene notes that it is possible to modernize credit scoring and allow lenders to consider information like rental and utility payments, which could expand homeownership for creditworthy first-time and low-income buyers, while preserving the ability-to-repay safeguards designed to prevent another wave of unsustainable mortgages. There is also political context here. The Trump administration has already been moving toward newer credit-scoring models, which means Boebert’s letter may be less intended as an attack on the administration and more as pressure to accelerate reforms that are already underway.
What happens next is still uncertain. Boebert’s proposal is not yet a bill, and it would not immediately change any mortgage rules even if it gained support. But the congresswoman says she intends to work closely with the Department of Housing and Urban Development, the Treasury Department, and the Department of Agriculture to develop concrete policy recommendations. She also says she hopes to eventually introduce bipartisan legislation aimed at making housing more attainable for today’s families. That’s an ambitious goal, especially in a political environment where bipartisan housing agreements are rare. Some skeptics, however, question whether this push is really about systemic reform or simply about political positioning. Thompson, for one, described the move as “Politics 101,” a way for Boebert to show herself aligned with everyday Americans struggling with housing costs. He argues that the affordability crisis is not fundamentally driven by underwriting procedures. It is driven by the fact that houses themselves are unaffordable because of their high cost and the current interest rate environment. In other words, no amount of flexible underwriting will fix the problem if wages cannot keep up with prices and the monthly costs of owning a home remain too high for the average family. Still, by raising these questions so publicly, Boebert has pulled an important conversation into the open. The dream of homeownership is not going away, and neither are the frustrations of those who have been shut out of that dream through no clear fault of their own. Whether the answer is lower down payments, broader credit scoring, or something else entirely, the underlying concern is painfully human: Americans want a fair chance to build a home and a future. And until the lending system catches up with the way they actually live and earn, that fair chance will remain, for many, just out of reach.