




JPMorgan: Bitcoin Poised to Outpace Gold as Institutional Hedges Unwind
By Market Research Desk | September 17, 2026
1. A Market Primed for an Inflection Point
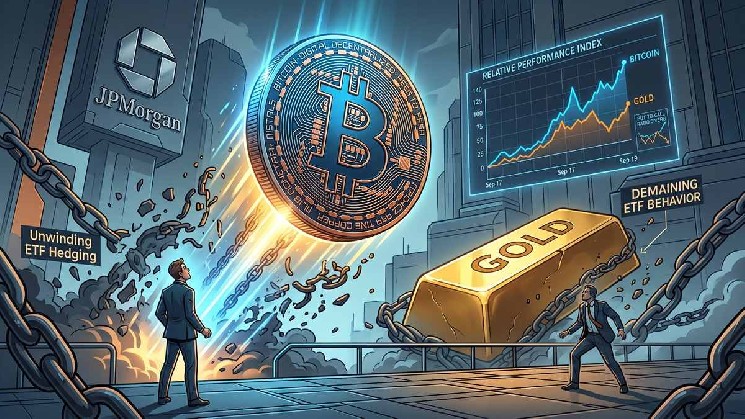
For much of 2026, gold has done exactly what investors expect of it: delivering a steady, dependable store of value in an era of lingering inflation concerns, elevated government spending and recurring geopolitical uncertainty. Bitcoin, meanwhile, has spent the same stretch navigating a far thornier path — one defined not so much by its fundamental adoption story, but by the sheer volume of defensive options and short positions wrapped around it. According to a new report from JPMorgan, published on Thursday, September 17, that contrast is about to become a pivotal plot point. The bank’s strategists believe Bitcoin is positioned to outperform gold over the coming months, provided institutional investors begin unwinding the protective hedges that have kept a lid on the cryptocurrency’s price.
The report, which quickly circulated among market participants and was flagged on social media by accounts tracking institutional positioning — including a widely shared post that framed it as exclusive market intel — lands at a delicate moment for both assets. Gold and digital currencies have drawn fresh institutional interest since the Federal Reserve’s July policy meeting concluded with a steadying of rate expectations. But the composition of that interest could hardly be more different. In gold, money managers are buying, and flows have been strong enough to erase every outflow the precious metal suffered earlier in the year. With Bitcoin, the flows have been more contained, and look beneath the surface and the derivatives market shows an investor base that has been accumulating protection rather than pursuing conviction. JPMorgan’s analysts, led by the prominent global markets strategist Nikolaos Panigirtzoglou, see that imbalance as the market’s most important structural feature — and potentially the most reliable catalyst for the next significant digital-asset rally.
2. Gold ETFs Recover Everything; Bitcoin ETFs Fight for Ground
The raw numbers from JPMorgan’s latest flows analysis lay the groundwork for the entire argument. Gold exchange-traded funds, the report reveals, have now recovered the entirety of the capital they lost during 2026. Every dollar of cumulative outflows from gold-backed products over the course of the year has been recouped by subsequent inflows, leaving the precious metal’s ETF complex in a position of undeniable institutional strength. It is a remarkable turnaround, particularly considering the severity of the February and April drawdowns, when risk-off sentiment swept through commodity markets and pushed portfolio managers toward cash and short-duration treasuries at the expense of hard assets. The rebound in gold ETF inflows since the spring has been impressive by any historical standard, reinforcing the notion that the metal retains its status as the default hedge among institutional allocators.
Bitcoin’s ETF sector tells a less complete story. Spot Bitcoin exchange-traded funds, led by BlackRock’s iShares Bitcoin Trust (IBIT), have recovered roughly half of the outflows recorded over the same period. The gap is significant: while gold has been embraced with open arms by institutional allocators, Bitcoin’s recovery has been comparatively tentative, halting and hedged. JPMorgan, however, refuses to read the tea leaves as a simple preference for gold over the cryptocurrency. Instead, the report frames the discrepancy as a function of hedging behavior. Institutional interest in Bitcoin is real, the bank suggests, but it has been systematically masked by the protective machinery that accompanies every ETF purchase — options overlays, collar strategies and short positions designed to limit downside in a notoriously volatile asset. Remove that machinery, and the true strength of demand could be exposed, with consequences for the relative performance of the two assets that have not yet been fully priced in by the market.
3. Short Interest on IBIT Sends a Loud-and-Clear Signal
Looking beneath the flow data, JPMorgan points to a clear divergence in short-selling activity across the two markets. Short interest on IBIT — a measure of how many shares have been borrowed and sold in anticipation of a price decline — is trading near its highest levels recorded during 2026. Throughout September, that reading has remained close to the annual ceiling, a persistent signal that a large cohort of market participants is positioned for weakness in Bitcoin. Whether those positions are outright bearish bets or structural hedges tied to the broader crypto exposure held in multi-asset portfolios, their sheer scale is itself a form of market intelligence that cannot be ignored.
The intelligence is all the more striking when set against gold. Short interest on the SPDR Gold Shares (GLD) ETF currently sits below its historical average, implying that traders see little reason to sell borrowed shares of the metal’s largest fund vehicle. The contrast could not be starker: the professional trading community is, at least in the short-selling arena, expressing considerably more skepticism about Bitcoin than about gold. From JPMorgan’s perspective, that asymmetry is precisely what makes the cryptocurrency more compelling as a relative trade in the months ahead. Elevated short interest represents a backlog of potential buy orders; in a rising market, short sellers are frequently compelled to cover their positions, adding fuel to a rally and amplifying the move. Gold, with its modest short interest, lacks that kind of upside powder. If Bitcoin prices begin to climb, the short-covering dynamic could give it an acceleration that GLD, for all its strength in spot flows, would struggle to match.
4. The Protective Wall in the Options Market
The options arena adds yet another layer to the thesis. JPMorgan’s analysis highlights the put-to-call open interest ratio on IBIT options — a standard gauge of whether traders are prioritizing downside protection or upside participation. That ratio, the report notes, has remained consistently above the historical average of equivalent instruments, notably options on GLD. For months, demand for put contracts on Bitcoin has outstripped what a neutral positioning stance would suggest. In other words, options traders have been insuring their spot holdings in Bitcoin at unusually high levels, a behavior pattern that has persisted even through periods of price stabilization.
At face value, that seems bearish. But JPMorgan frames it as an expensive insurance policy — one that, like all insurance, is likely to lapse eventually. When the perceived risk of a sharp drawdown subsides, whether because of a friendlier regulatory environment, a dovish pivot from the Federal Reserve, or simply the passage of time in a stable market, the need for those puts evaporates. Traders stop buying new protection, existing put positions are allowed to expire worthless, and the market is left with a significantly higher net long exposure than the raw flow data ever suggested. The report argues that Bitcoin’s current options profile is the single clearest indicator that a hedge-unwind rally could be in the offing. It is a mechanism that has played out repeatedly in other volatile asset classes, from equities to emerging-market currencies, and the firm sees no structural reason why it should not apply to Bitcoin — or why gold, with its comparatively tame options metrics, should benefit to the same degree. For the bank’s trading clients, the message is clear: the protective wall around Bitcoin is higher and thicker than anything surrounding gold, and when it begins to crumble, the release of institutional buying pressure is likely to be sharp.
5. From $90,000 to $77,000: JPMorgan’s Evolving Framework
JPMorgan’s conviction in this call has developed gradually through the year, shaped by an evolving assessment of Bitcoin’s underlying economics and its fair value relative to traditional stores of wealth. The bank began 2026 with an estimate of the average production cost of Bitcoin at $90,000 — the figure it viewed as the marginal cost of mining a single coin, and a rough floor for the asset’s value in the firm’s models. By early February, however, that estimate had been revised down to $77,000, reflecting improvements in mining hardware efficiency, falling energy costs in key production regions and a shifting reward structure that altered the economics of adding new supply to the network.
The narrative took another important twist in June, when JPMorgan’s analysts observed that Bitcoin’s market price had spent five consecutive months below that estimated extraction cost. With the price languishing beneath the cost of production, miners faced a challenging environment, and the market was effectively signaling that the asset was undervalued relative to its supply-side fundamentals. Meanwhile, the bank’s longer-term, volatility-adjusted models continued to suggest that a fair value far above the prevailing market price was justified. Benchmarking against the global volume of gold — the standard methodology the bank has used for years to derive a theoretical price target for the cryptocurrency — JPMorgan’s model yields a valuation of approximately $266,000. That figure has appeared in previous research notes and continues to anchor the bank’s longer-term view that, on a risk-adjusted basis, Bitcoin remains substantially undervalued relative to its traditional counterpart. The persistence of institutional hedging, the report contends, is one of the principal reasons such valuations remain confined to spreadsheets rather than price charts — and why the unwinding of those hedges could close that gap with surprising speed.
6. Catalysts, Clouds, and a Crowded Calendar
The near-term catalysts for a partial or full unwind of those protective positions are clustered on the late-September calendar. Trading desks across the industry are closely monitoring the end of the third quarter of 2026, a period when institutional portfolios are routinely rebalanced and when crowded trades tend to hit their inflection points. Even more significant is the Federal Open Market Committee (FOMC) monetary policy meeting scheduled for late this month. A dovish signal from the Fed — or even a neutral outcome that disappoints the market’s more hawkish voices — could provide the trigger for institutional investors to reassess their defensive positioning in Bitcoin. Anything that reduces the perceived tail risk of a macroeconomic shock is likely to reduce the demand for put protection.
But the path is not without obstacles. JPMorgan has been vocal through the summer about the legislative headwinds facing the crypto industry. The bank has specifically warned that the window for advancing the Clarity Act, a bill drafted to establish a coherent regulatory framework for digital assets in the United States, is narrowing in Congress. For many institutional investors, that unresolved uncertainty remains a genuine barrier to conviction — one that could delay or diminish the hedge-unwind trade the bank anticipates. Still, the asymmetry of the current setup is difficult to overlook. Gold has already recovered its outflows; Bitcoin has not. Short interest on IBIT is near its annual highs; short interest on GLD is subdued. The options market is paying heavy premiums for downside protection on Bitcoin and only modest premiums on gold. JPMorgan’s conclusion is characteristically clinical: the scales are tilted, and when they finally reset, the release of tension could produce the long-awaited moment when Bitcoin — not gold — leads the institutional charge. For a market that has spent most of the year waiting for clarity, the bank’s report offers a timely reminder that the biggest moves often begin not with a headline event, but with the quiet unraveling of protection.