

BitGo Launches Bitcoin Staking for Institutional Custody Clients, Powered by Stacks
Bitcoin Staking Arrives Inside a Chartered Bank Custody Framework
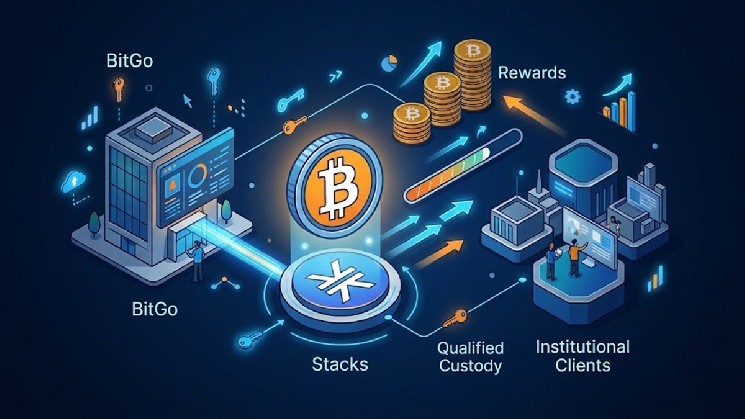
BitGo has crossed a threshold that many in the crypto industry thought might still be years away: institutional clients can now earn Bitcoin rewards on Bitcoin that never leaves qualified custody. The announcement, made public on Nov. 3, brings together BitGo Bank & Trust, National Association, a federally chartered trust bank, and the Stacks blockchain in a partnership that effectively delivers Bitcoin staking through a regulated custody structure. Eligible qualified custody clients can earn BTC rewards on bitcoin held in BitGo Bank & Trust accounts, with the underlying Bitcoin protected in a timelocked vault on the Bitcoin network throughout the staking period. This is not a lending product and it does not involve transferring assets to a separate protocol or trading venue. Instead, the Bitcoin remains under the authority of a qualified custodian while the Stacks network provides the economic infrastructure that generates rewards. For institutional investors that have long watched Bitcoin sit idle in cold storage while traditional fixed-income assets produced yield, the arrival of a bank-backed staking product is a significant development. It begins to answer a question that has hovered over Bitcoin since the earliest days of the institutional adoption wave: can Bitcoin itself produce income without being exposed to counterparty risk or moved off a secure custody platform?
The mechanics of the service reflect a careful effort to maintain security while opening up new possibilities. According to the terms of the arrangement, participating institutions are required to lock up an STX position equivalent to 5% of the value of the Bitcoin they choose to stake. Both the Bitcoin principal and the STX collateral remain committed for a period of approximately six months. At the end of that term, the Bitcoin principal becomes available again under the bond terms, meaning there is a defined timeline rather than an open-ended commitment. The structure gives institutions a clear sense of when their assets will be unlocked and what they are earning during the lockup. It also ensures that the staking mechanism is not a black box. Bitcoin is secured on the main chain, STX collateral is committed on the Stacks side, and rewards are settled in Bitcoin. For compliance teams and risk managers inside large financial institutions, that level of clarity matters enormously. It creates a transparent paper trail for auditors, a clear legal framework for custodians, and a straightforward accounting treatment for the assets involved. In a market where some digital asset products have been criticized for opaqueness, the BitGo approach is an attempt to bring institutional-grade discipline to Bitcoin yield generation.
Inside the Stacks Mechanism: How Bitcoin Rewards Are Produced
Bitcoin has never been a native proof-of-stake network, and that has historically made the concept of Bitcoin staking complicated. Ethereum and other smart contract platforms allow users to lock tokens to secure the network and earn rewards, but Bitcoin’s proof-of-work consensus is built around computing power rather than locked capital. Stacks solves that problem with a mechanism called Proof of Transfer, or PoX-5, which connects Bitcoin transactions to activity on the Stacks blockchain in a way that creates a genuine reward stream for Bitcoin holders. Under this model, Stacks miners are required to commit Bitcoin to compete for the right to produce blocks on the Stacks network. That Bitcoin is then used to fund rewards for participants who lock their own assets in staking-related bonds. The result is a system that does not require Bitcoin to change its consensus mechanism or sacrifice its security properties. Instead, Stacks leverages Bitcoin’s existing network and liquidity while adding a separate layer where stacking, the Stacks term for staking, can generate returns.
The specific structure that BitGo is using relies on what the Stacks community calls a genesis bond. Participants lock their Bitcoin, add an STX collateral position, and commit both for a set period. During that time, Bitcoin rewards are generated from the pool of BTC committed by miners. One of the distinguishing features of this approach is that the rewards are denominated in Bitcoin itself, not in STX. That may sound like a small detail, but it is actually a major design choice. Institutions that hold Bitcoin want to earn Bitcoin, not a separate token that they must then sell or convert. Earning STX would introduce an additional layer of tax complexity, market volatility, and portfolio rebalancing work. By paying rewards in BTC, BitGo and Stacks have made the product far more usable for treasury teams and fund managers who need to report performance in Bitcoin terms. Stacks founder Muneeb Ali has pointed to an annual target rate of around 3%, although actual distributions will depend on miner activity, transaction fees, and payment timing. That distinction is crucial. A target rate is not a guaranteed rate, and institutions looking for a fixed coupon will need to temper their expectations. But in a world where many digital asset yield products have failed because they promised too much, the more conservative framing is probably a strength rather than a weakness.
A Custody-First Design That Keeps Bitcoin Secure and Separate
Security and operational transparency are at the core of the BitGo offering. The Bitcoin that is being staked is not sent to a decentralized smart contract or pooled in a commingled wallet. Instead, it remains in a timelocked vault on the Bitcoin network, with BitGo Bank & Trust, National Association, acting as the qualified custodian throughout the process. This is a meaningful distinction for institutions that operate within strict regulatory frameworks. A qualified custodian is not merely a technology provider; it is a regulated entity responsible for the safekeeping of client assets under applicable banking and trust law. By placing the staking process inside that structure, BitGo has effectively eliminated one of the biggest barriers that kept conservative institutions on the sidelines: the fear that Bitcoin staking would require them to hand their assets over to an unregulated protocol with unclear legal status. The timelock itself is an on-chain mechanism that prevents the Bitcoin from being moved before the bond term expires. That gives clients a verifiable guarantee, rather than a contractual promise alone, that their principal is not at risk of being deployed elsewhere.
The service also addresses one of the more practical challenges facing ETF and ETP issuers in the digital asset space: how to keep staking rewards separate from principal holdings. BitGo supports separate addresses for staking rewards and Bitcoin principal, which means that fund accountants can clearly distinguish between the underlying investments and the income they generate. For an ETF or ETP sponsor, this level of accounting clarity is essential. Fund valuation rules, disclosure requirements, and tax reporting often hinge on whether income is being recorded in the correct place. A commingled structure could create audit headaches and potentially raise concerns with regulators. By building separate address architecture into the service, BitGo has made it possible for institutions to add Bitcoin staking to their products without disrupting their existing custody and reporting workflows. That operational flexibility may be the quiet force that drives broader adoption across the asset management industry. It is one thing to say that Bitcoin staking is safe; it is another to show that it can be integrated into the complex operational machinery of a regulated fund.
Early Evidence From the First Genesis Bond Shows Strong Coverage
The real-world test for any new staking mechanism is whether the reward pool actually has enough capital to meet its obligations. Early data from the Stacks ecosystem suggests that the model is holding up well, at least in its initial phase. According to a report from Alea Research published on Nov. 3, the first Genesis Bond opened on Sept. 10, pairing 230 BTC with approximately 3.57 million STX. During its first full payment cycle, miner contributions covered the bond’s scheduled payment 17.9 times, well above the 2x coverage target established under SIP-045, the Stacks improvement proposal that governs the relevant parts of the PoX-5 protocol. To put that in perspective, a coverage ratio of 17.9 means that the amount of Bitcoin committed by miners was nearly eighteen times what was needed to satisfy the bond’s payment obligations. That surplus offers a significant margin of safety and suggests that the network is generating far more Bitcoin than it currently needs to distribute. It also indicates that miners see real value in participating on the Stacks network, despite the fact that they must commit real BTC to do so.
Coverage ratios are important, but they do not tell the whole story. The staking ecosystem is still young, and miner participation, fee volatility, and broader market conditions will inevitably influence future payment cycles. A strong first cycle does not guarantee that every subsequent cycle will produce the same results. Still, the initial data provides a useful baseline for institutions considering whether to allocate capital to this product. It demonstrates that the mechanism works in practice and that the reward stream is not simply theoretical. For institutions that have been burned by overhyped yield products in the past, the availability of verifiable on-chain data and independent research reports matters a great deal. The 17.9x coverage ratio is the kind of detail that gives a story credibility. It is not a marketing slogan; it is a number that can be checked, audited, and analyzed. In that sense, the BitGo-Stacks partnership is not just introducing another crypto yield product. It is bringing a more mature, evidence-driven approach to a market that has often lacked it.
Why Bitcoin Rewards, Not Protocol Tokens, Matter for Institutional Adoption
One of the most carefully considered aspects of the BitGo product is the decision to pay rewards in Bitcoin rather than in STX. That single choice has ripple effects across the entire institutional user experience. When an institution earns rewards in a volatile token, it has to think about market-making, liquidation schedules, and the possibility that the value of the reward could decline before it is sold or converted. Earning Bitcoin, by contrast, keeps the entire transaction inside an asset class that the institution already understands and already holds. It also makes treasury management simpler. A Bitcoin-denominated reward stream can be recorded, valued, and monitored using the same systems that already track the institution’s primary Bitcoin holdings. There is no need to stand up a separate token custody operation or hire a specialist team to navigate a less familiar digital asset. For many institutions, that operational efficiency could be the deciding factor between participating in Bitcoin staking and continuing to hold Bitcoin passively.
There is also a psychological dimension to this decision. Institutional investors tend to be more comfortable with assets that have established liquidity, clear regulatory treatment, and a long track record. Bitcoin has all of those qualities, even in the eyes of conservative investors. STX, by contrast, is a smaller and younger token, and while it has a real role in the Stacks ecosystem, it does not carry the same institutional weight as Bitcoin. By aligning the rewards with the core asset, BitGo is effectively lowering the perceived risk of the product. It is easier for an investment committee to approve a product that earns Bitcoin on Bitcoin than one that earns an unfamiliar protocol token that the committee may not fully understand. This insight has been lost on some other projects in the digital asset space, but BitGo’s approach suggests a strong understanding of what institutional clients actually want: simplicity, security, and returns in a recognizable form.
A New Chapter for Institutional Bitcoin Yield
The launch of Bitcoin staking through BitGo Bank & Trust could mark the beginning of a broader trend. For years, the conversation around digital asset yield has been dominated by decentralized finance platforms that require users to take on substantial smart contract risk and navigate complex technology. Those platforms have served a purpose, but they have never been comfortable for large institutions. The BitGo integration changes the narrative by bringing Bitcoin staking into a regulated environment where client assets remain under the control of a qualified custodian. It opens the door for banks, asset managers, insurance companies, and other institutional investors to explore Bitcoin yield strategies without crossing the lines that their compliance departments have drawn around self-custody and protocol risk.
That said, this is still early days. The service is being rolled out to eligible qualified custody clients, and not every account will qualify. The 5% STX collateral requirement and the six-month lockup period are conditions that some investors may find restrictive. The 3% target rate is attractive in a low-yield environment, but it is not guaranteed, and the actual return will depend on the health of the Stacks mining economy. Institutions will need to conduct their own due diligence, monitor coverage ratios, and assess whether the product fits within their broader portfolio strategy. What the launch does provide, however, is a proof point that Bitcoin staking can be built at the institutional level with the same security, transparency, and operational rigor that investors expect from traditional finance. Whether the model scales and whether other custodians follow BitGo’s lead remains to be seen. But the direction is clear: Bitcoin is no longer just a static store of value. With the right infrastructure, it can be an active, yield-generating asset, even inside the walls of a regulated bank.