

After an 80% Slide, Is Gemini Space Station a Takeover Target?
A sudden fall from the top
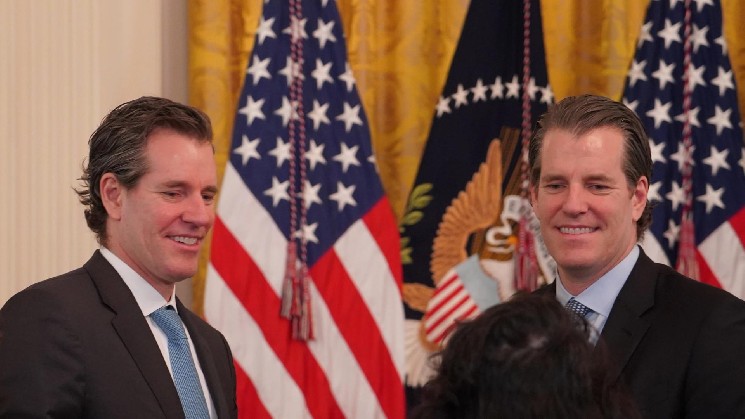
Since Gemini Space Station made its public trading debut, the crypto platform founded by billionaire twins Cameron and Tyler Winklevoss has watched its market value disintegrate. The price of GEMI, the platform’s listed security, has fallen by roughly 80 percent since that debut. At its peak, the venture was valued at close to $4 billion. Today, its market capitalization hovers around just $753 million. That is a staggering reversal for a company that once stood as one of the most recognizable and carefully branded names in American crypto — a symbol of the industry’s attempt to build trust with regulators, banks, and institutional investors. The sudden collapse has revived a question that would have seemed almost unthinkable during the platform’s heyday: Could the Winklevoss twins’ creation eventually become an acquisition target? The idea is not as strange as it might sound. In any market, a sharp decline in valuation can turn an admired leader into a potential takeover candidate. But in crypto, where regulatory trust is far harder to build than trading engines, the calculus is unusual. Gemini’s infrastructure, its licenses, and its compliance system may now be worth more than the revenue it is currently generating. The platform’s shrinking spot-exchange business is a serious problem, but the platform’s permissioned, well-policed entrance into the U.S. market is an asset that other firms would struggle to replicate. The question is not just what Gemini is worth today; it is what the platform could be worth in the hands of a buyer that desperately needs a regulated gateway into the world’s largest capital market.
The numbers behind the distress
The latest operating figures make for uncomfortable reading. Gemini’s second-quarter exchange revenue fell 38 percent from the same period a year earlier, landing at just $12.5 million. Spot trading volume dropped even more sharply, plunging 66 percent to $3.8 billion. Meanwhile, assets held on the platform slid from $18.2 billion to $8.4 billion. These are not the numbers of a company in growth mode; they describe a business in retreat. Trading volume has migrated to derivatives, to offshore venues, and to competitors like Coinbase, Kraken, and a long tail of decentralized exchanges. The U.S. spot market is no longer the guaranteed revenue machine it was during the boom years, and Gemini has felt that shift more acutely than most. But there is another way to read these numbers. The market cap has fallen so far that a strategic buyer could potentially pay a substantial premium and still come out ahead if the value lies in the regulatory shell rather than the trading volume. The company’s current valuation implies that its licenses, its bank relationships, its custody infrastructure, and its ability to legally serve American customers are worth almost nothing. That is a strange outcome for a platform that spent more than a decade building exactly those capabilities. The more the spot business shrinks, the more Gemini begins to resemble an asset play rather than an operating company — and the more likely it becomes that someone else will try to put that asset to better use.
A takeover blueprint from ARK Invest
The most striking proposal in that direction came last month from Lorenzo Valente, director of digital assets research at ARK Invest. In a post on X, Valente argued that Hyperliquid, the offshore perpetual-trading platform known for its speed and its deep pool of derivatives liquidity, should acquire Gemini and use it as a regulated U.S. gateway for perpetual futures and prediction markets. The logic is straightforward. Hyperliquid has the product and the technology, but it lacks the legal authority to serve U.S. customers on a fully regulated basis. Gemini has the authority, but it has been losing ground in a brutal spot-trading market. Together, the two could cover each other’s blind spots. Hyperliquid would gain access to American users without having to build a compliance-heavy entity from scratch, while Gemini would gain a product suite that matches modern crypto demand. Valente also pointed to a structural detail that matters more in M&A than most people realize: the Winklevoss twins’ concentrated voting control. That means a transaction would not require convincing a scattered shareholder base or fighting a noisy activist campaign. A deal could be negotiated with a small number of decision-makers — assuming, of course, that the twins are willing to sell. There is no public indication that Hyperliquid is actively pursuing Gemini, and Valente’s post should be read as an analyst’s argument, not a formal offer. But the fact that such a proposal is being discussed openly says a great deal about how far Gemini’s market position has shifted.
Why the real value is regulatory
What makes this more than a fringe theory is the broader direction of the digital asset market. Spot trading has become a low-margin, hypercompetitive commodity business. Derivatives, especially perpetual futures, are where the real revenue is concentrated. Prediction markets, meanwhile, have become one of the fastest-growing corners of crypto, as users flock to platforms that let them trade the outcomes of elections, policy decisions, and cultural moments. But none of that matters if a platform cannot legally serve American customers. That is where Gemini’s value proposition becomes clear. The platform spent years building the kind of infrastructure that cannot be purchased off the shelf: a New York trust charter, state money transmitter licenses, institutional custody systems, compliance teams, and relationships with banks and auditors. Recreating that infrastructure would take years and cost far more than Gemini’s current market capitalization. For Hyperliquid, or any other buyer, buying Gemini would be a fast track into the most important financial market in the world. It would also bring a brand that still carries weight in Washington and on Wall Street. In crypto, almost every major platform would like to be regulated in the U.S., but very few understand the price of entry. Gemini has already paid that price, and the market is currently giving it away at a steep discount. The platform’s regulatory infrastructure, in other words, may be the most valuable thing it owns — and the most compelling reason for a takeover.
Why a deal still might not happen
Still, a transaction is far from certain. Hyperliquid has given no official indication that it is pursuing Gemini, and Valente’s proposal has not been followed by any public negotiating process. Regulatory hurdles alone could discourage a buyer. Gemini operates as a licensed trust company in New York, and any change of control would trigger a detailed review by state and federal authorities. An offshore derivatives platform seeking to acquire a U.S. regulated crypto company would face intense scrutiny, and regulators could impose conditions that would make the deal less appealing. Then there are the founders themselves. Cameron and Tyler Winklevoss have spent more than a decade positioning Gemini as the responsible, regulation-first alternative to the chaotic offshore world. Selling to Hyperliquid — an offshore perpetual-trading platform — would be an ironic ending to that story, and no amount of strategic logic can erase the personal and reputational dimensions of such a decision. The valuation gap is another issue. Gemini’s public market capitalization may be down, but the twins are likely to believe their platform is worth far more than the current price reflects. If a buyer wants to pay a premium for regulatory assets, the sellers may demand a price that eliminates the financial logic. There is also the cultural challenge. Crypto-native speed and compliance-heavy caution do not always mix well, and a potential acquisition could be complicated by very different views on how to run a platform.
The road ahead for GEMI and the Winklevoss twins
Where does all of this leave investors in GEMI? The asset has already lost roughly 80 percent of its value, which means the market has priced in a punishing outlook. But distressed crypto assets have a way of surprising people. If a credible buyer emerges, the possibility of a takeover premium is real. If no deal materializes, Gemini could try to reinvent itself as a regulated derivatives and prediction-market platform, using the infrastructure it already owns to enter higher-margin businesses. It could also narrow its focus to institutional custody and high-net-worth clients, areas where its compliance-first reputation still matters. What seems increasingly clear is that Gemini’s future no longer lies in ordinary spot exchange trading. The platform needs a new strategy, a new product line, or a new parent. The Winklevoss twins will ultimately make that decision, and whatever they choose will shape the next chapter for the company and for the GEMI holders who have already suffered a steep decline. In a market built on narratives, a takeover story is one of the few forces that can turn a prolonged downturn into a sudden comeback. Whether Gemini becomes an acquisition target or an independent comeback story, the next few months are likely to be decisive. The platform may have lost its old identity, but it has not lost the infrastructure that once made it a pioneer. The real question is who gets to control that infrastructure next.