

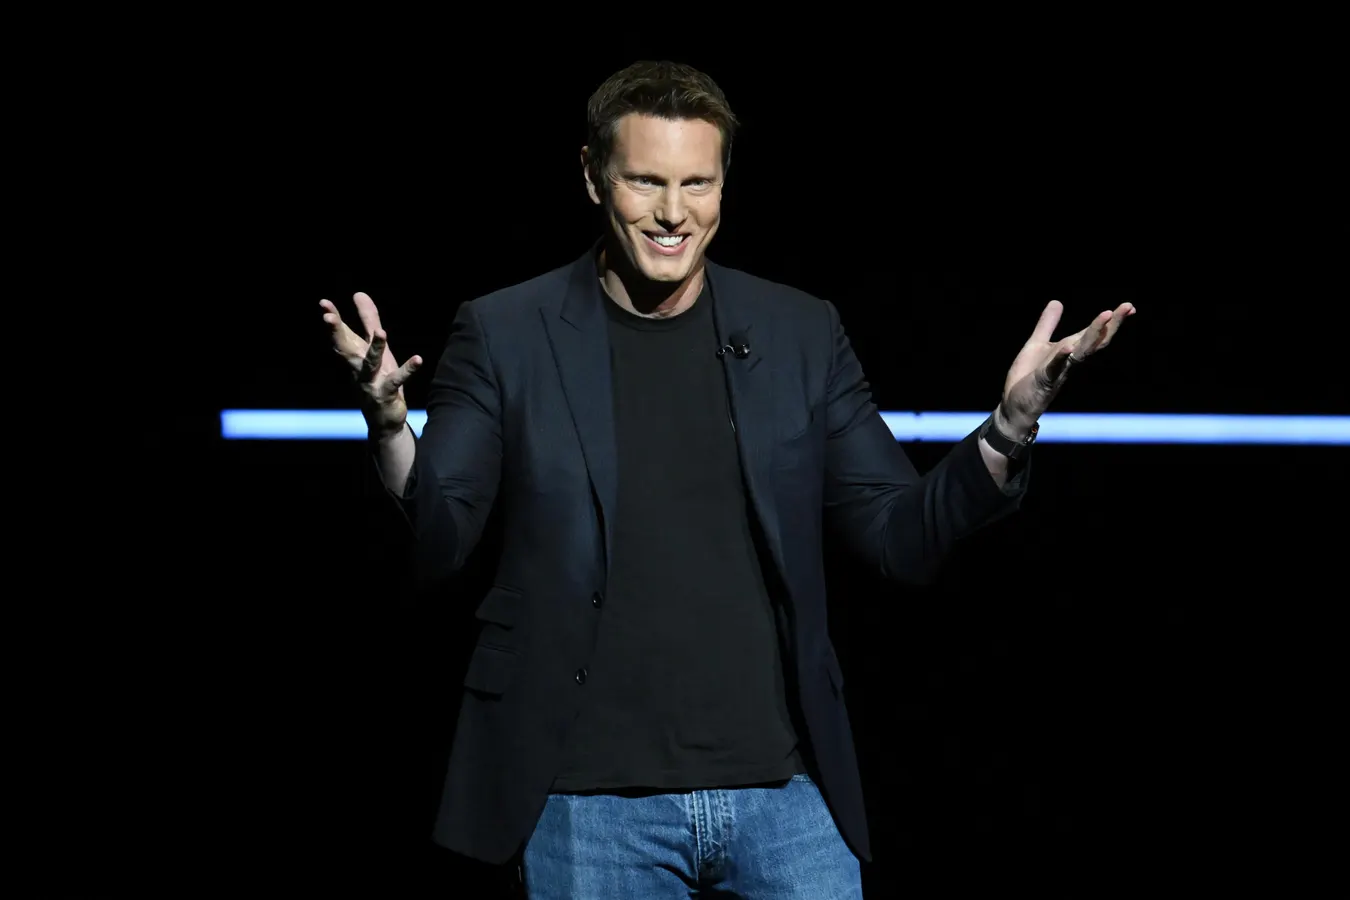
For most people, a $150 million payday would be the kind of windfall that changes everything—the kind of number that buys a private island, ends generations of financial worry, and makes headlines in its own right. For David Ellison, though, it is closer to pocket change. This week, Paramount Skydance finally closed its long, bruising takeover of Warner Bros. Discovery, creating a media titan that stretches from CBS and Paramount Pictures to HBO, CNN, and the Warner Bros. movie studio. The combined company will be renamed simply Skydance, and David Ellison, its chief executive, now sits atop one of the most storied entertainment empires in Hollywood history. Climbing into that chair came with a $150 million reward—a blend of cash bonus and restricted stock meant to celebrate the deal’s completion. To almost anyone else, that would be a life-changing fortune. To David, it is a rounding error in a family story defined by almost unimaginable wealth. His father, Larry Ellison, co-founded Oracle and is the world’s eighth-richest person, with an estimated net worth of $185 billion. David’s own fortune, estimated by Forbes at more than $1 billion, is real enough, thanks to the merger windfall, his existing Paramount stock, and a collection of homes. But the deeper truth is that nearly all of it traces back to his father. Larry backed David’s original production company, supplied much of the equity for the Paramount acquisition, and personally guaranteed more than $45 billion of this week’s $110 billion megamerger. David controls what amounts to the family’s voting power—nearly all of its 77.5 percent control of the new company—but the actual money behind that control is overwhelmingly Larry’s. It is a deliberately complicated, often opaque arrangement, and it speaks volumes about how enormous wealth is passed down, and how hard it is to separate a person’s own accomplishments from the inheritance that made them possible.
Forbes, for its part, tends to treat wealth this way: when the founder of a fortune is still alive, that fortune is credited to the founder, even if some of it has been handed to heirs. That is why David Ellison does not appear on the World’s Billionaires list, despite being a billionaire by any practical measure. His fortune is folded under “Larry & family,” a category that captures the reality of the Ellison household: one man built the money, and his children have been absorbing pieces of it their entire lives. David was born in 1983, alongside his sister Megan, to Barbara Boothe, Larry’s third wife out of six. Their childhood was shaped by Larry’s absence during the years he was turning Oracle into a database giant. Friends have said Larry later regretted missing so much of his children’s early years, a quiet ache that may help explain why he has been so generous, and so present, in their adult ambitions. When Oracle went public in 1986, Larry set aside 90,000 shares for David, then three years old, and the same for newborn Megan. After multiple stock splits, that stake would now be worth more than $4 billion. But by 2012, the last time the number was publicly disclosed, it had shrunk to under one million shares. What happened to the rest is unclear, though Forbes estimates that if David’s half was sold gradually, taxed, and invested conservatively, it would be worth around $300 million today. The children also received similar stakes in NetSuite, a business software company Larry backed early on. When Oracle bought NetSuite in 2016, David’s trust collected about $370 million before taxes—a sum Forbes estimates would be worth roughly $500 million today. These are not ordinary allowances. They are the mechanics of a family fortune moving from one generation to the next, sometimes in ways that look like gifts, sometimes in ways that look like investments, and always with the same quiet source.
What brought father and son together, in the end, was flying. David saw Top Gun as a child and was immediately hooked—the speed, the danger, the sheer romance of flight. His father gave him his first plane when he was thirteen. At sixteen, he soloed. At twenty, he became the youngest member of an elite stunt-flying team at the Oshkosh air show, performing aerobatics in front of crowds and learning the kind of discipline and nerve that ordinary classrooms could never teach. He is still a licensed pilot today, and the love of flight never really left him. It was that passion that eventually led him to Hollywood. While studying film at USC, David was cast in Flyboys, a 2006 World War I movie about American pilots who volunteered for France before the United States entered the war. It was a vanity project in some ways, and an expensive one: the film reportedly cost its investors—largely Larry Ellison—around $65 million, and it earned only about $18 million at the box office. It was a humbling failure, but David did not let it define him. He quit acting, dropped out of college, and used his father’s money to start his own production company, naming it Skydance after the stunt-flying term. The company initially produced smaller films, but its first real breakthrough came with True Grit in 2011. That success led to a partnership with Paramount that produced blockbuster franchises: five Mission: Impossible movies, two Star Trek films, and eventually Top Gun: Maverick—the sequel to the very movie that had first made him dream of flying. His sister Megan took a different, riskier path in independent film, scoring hits like Zero Dark Thirty and American Hustle before financial troubles forced her to seek a bailout from Larry in 2019. David, by contrast, seemed to be building something bigger, with more discipline and a clearer eye on the future.
David’s ambitions, it turns out, were far larger than anyone suspected. In 2024, he shocked the entertainment world by winning the long, messy race to buy Paramount from Shari Redstone, its longtime owner. The offer was $8 billion, and roughly $6 billion of that came directly from his father, with private equity firm RedBird Capital supplying the rest. The deal closed in August 2025, and just as the industry was catching its breath, David went after an even bigger fish: Warner Bros. Discovery. People who know the Ellison family describe David as the golden child, and watching him move from one enormous acquisition to the next, with his father’s wallet behind him, it is easy to see why. But the Warner deal was not easy. It took nearly a year of intense, bruising negotiation. Warner Bros. initially agreed to sell itself to Netflix in December, and for a while that seemed inevitable. David, however, launched a hostile bid and kept raising his price until Netflix walked away in February. The final offer was $110 billion, and more than 40 percent of it was guaranteed by Larry personally. Twelve state attorneys general sued to block the transaction on antitrust grounds, arguing that the combination of two massive studios would hurt competition and consumers. The lawsuit was settled last month, with Paramount agreeing to a series of conditions, including a commitment to protect the independence of CNN. The whole process was a masterclass in how modern media consolidation works—mixing brute financial force, political negotiation, legal maneuvering, and relentless personal ambition.
Now that the deal is done, David Ellison faces the hardest task of all: actually running the empire he has assembled. Two aging studio systems—Paramount and Warner Bros.—must now be steered through an industry upended by streaming, where audiences are fickle, budgets are enormous, and debt is piling up. The new company carries billions in debt, and the pressure to make the math work will be relentless. David is not in the same position his father was when he was building Oracle, inventing a new category and defining the rules as he went. He is instead inheriting legacy institutions, filled with beloved brands but also with decades of accumulated bureaucracy, creative misfires, and financial strain. He has no proven track record as a media operator; he has mostly been a financier and producer, backing other people’s visions rather than managing a sprawling conglomerate day to day. But he has something that almost no one else has: the absolute, unquestioning financial support of one of the richest men in human history, and the freedom that comes with it. That support gives him time, room to make mistakes, and the ability to wait out failures that would ruin other executives. It also gives him something subtler, and perhaps more important: the confidence that comes from knowing the family name is never really at risk, no matter how badly a movie flops or a quarter disappoints. Whether that confidence translates into wise leadership remains an open question. Hollywood is littered with the wreckage of wealthy heirs who thought they could simply buy their way into the industry and then command it through force of will.
In the end, David Ellison’s story is a story about family, money, and the strange ways they intertwine. He was born into a fortune so vast that most of us cannot begin to imagine it, and he has spent his life figuring out what to do with that inheritance. His father was absent at the start, building the empire that would define the family, and then spent years trying to make up for that absence by funding his children’s dreams, no matter how costly or uncertain. David chose flying, then Hollywood, then the entire entertainment industry, and his father backed every step with staggering sums of money and personal guarantees. The $150 million bonus he received for closing this week’s transaction is a token of the system that made him, a symbolic gesture in a family where money is both the oxygen and the language. He will now have to prove he can do more than assemble the pieces. He will have to produce good movies, keep networks alive, manage fragile egos, pay down enormous debt, and satisfy shareholders who will not accept losses forever. He will have to be, in some ways, the exact opposite of the golden child: someone willing to be unpopular, to make hard cuts, to take responsibility for failures that cannot be blamed on anyone else. The pained negotiations, the antitrust lawsuits, and the eye-watering guarantees were all just the beginning. The real test begins now, in the quiet offices and editing rooms where the fate of Skydance—and the Ellison family’s bet on Hollywood—will be decided. David has the money, the control, and the mandate. What he does with them, now that his father’s billions are no longer just a cushion but a burden, is the only question that matters.