

Bitcoin Open Interest Shrank, but the Risk Is Still Hiding in the Details
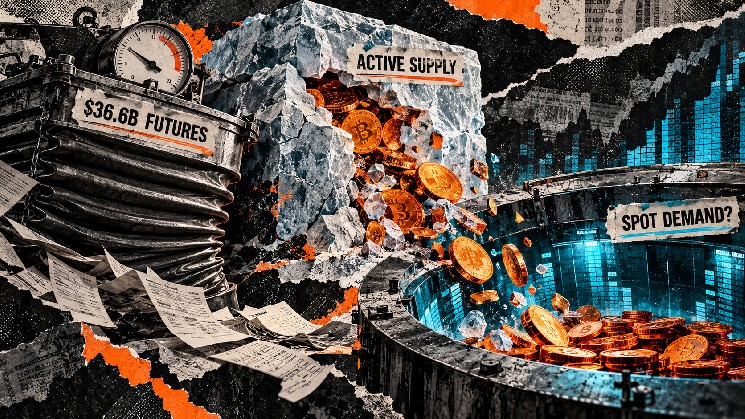
For much of the past year, traders and analysts have treated Bitcoin’s open interest as one of the most reliable pulse points for the crypto derivatives market. The logic is straightforward: more outstanding futures contracts generally mean more speculative activity and, by extension, more potential volatility. But Glassnode, one of the leading on-chain analytics firms, is urging the market to think beyond that single number. In its latest report, the firm points out that open interest only measures the total amount of outstanding futures exposure. It says nothing about how leveraged those positions are, what type of collateral sits behind them, or how vulnerable the market might be to a sudden price move. That distinction is not just academic. The latest October snapshot shows a derivatives landscape that has contracted from its earlier highs, but the remaining exposure is still near the upper edge of Glassnode’s statistical range. In other words, the market has not cleaned itself out. What happened instead is a shift in the texture of risk, not a disappearance of it. Leverage can hide inside a smaller open interest number, especially if a concentrated group of traders controls a large share of the positioning. Collateral quality matters as well; positions backed by volatile assets can unwind more violently than those backed by stablecoins or cash. The report’s message is that open interest is a starting point, not a destination.
The first sign that something more nuanced is happening can be found in funding rates. Perpetual swaps, the most popular type of crypto futures, rely on a periodic funding payment between longs and shorts to keep the contract price anchored to the spot price. When long-side funding payments rise, it means bullish traders are willing to pay a premium to maintain their positions. According to Glassnode’s data, those payments increased from $926,400 to $1.5 million during the reporting period. That happened even as open interest contracted. This is a surprising combination at first glance: fewer total contracts, yet stronger demand for bullish exposure. The two metrics are not contradictory, but they illustrate how quickly sentiment and positioning can diverge in digital asset markets. One explanation is that traders are consolidating their exposure, reducing the size of total positions while showing more conviction in the direction of the trade. Another is that a smaller but more aggressive cohort of leveraged long buyers is driving the market. Either way, the rising funding payment adds a cautionary layer to the story. It suggests that the shrinking derivatives footprint is not necessarily a sign of fading interest. It could just mean the remaining interest is more concentrated, more leveraged, or both. For risk managers, that distinction matters because concentrated leveraged positioning can amplify sudden price swings, particularly when the funding curve flips and long traders are forced to unwind at the same moment. Glassnode’s point is not that a sharp reversal is imminent, but that the structural fragility of the market cannot be gauged from open interest alone.
To see where the real pressure is building, Glassnode turns to on-chain behavior. The firm’s March 2025 Market Pulse glossary defines Hot Capital Share as a measure of Bitcoin’s supply that has moved within a three-month window. The concept is based on realized-cap age bands, a methodology that has become central to modern on-chain analysis. Rather than valuing each coin at the current market price, realized capitalization values it at the price when it last moved on the blockchain. Each age band’s value is then divided by the total realized capitalization, which represents the combined last-movement value of the entire coin supply. When an older coin moves, its age resets and its realized value is updated to the current transaction price. That means an established holder who sends coins for the first time in years can suddenly increase the economic weight of recently active capital, even if no new money has entered the market. This is a subtle but important point. Rising hot capital is often interpreted as a sign of new demand, but Glassnode is careful to note that activity alone cannot identify first-time investors or fresh fiat deposits. A seasoned whale moving a large stash can generate the same signal as a retail investor opening a brand-new position. For that reason, the changing mix of coin ages is best understood as a measure of sensitivity, not as a clean barometer of new participation. It tells you that more of the supply is capable of moving quickly, but it does not tell you who will transact next, or in which direction. Still, the shift matters because it changes the market’s reaction function to future shocks. When a greater percentage of supply is recently active, the potential for a fast sell-off in a downturn is higher. The question is whether that potential will be realized, and that depends on the broader demand picture.
The shift toward a more reactive supply is visible in another Glassnode metric: the short-term to long-term holder supply ratio. At 14.2%, the ratio means that for every 100 units of supply held by long-term investors, there are roughly 14.2 units held by short-term investors. That might not sound extreme, but it represents an important change in the composition of the market. Glassnode’s holder classification is not based on individual wallets or personal identities. Instead, the firm groups addresses into entities and smooths their entity-average holding-age classification around a 155-day midpoint, while excluding exchange balances. The result is a behavioral proxy that distinguishes between investors who have held through market cycles and actors who are more likely to respond to short-term price action. Younger cohorts tend to spend far more readily during volatility. They are the traders who set stop-losses, rotate into other assets, or take profits at the first sign of momentum shifting. Their growing relative presence in the supply mix supports continued price sensitivity, but it leaves the timing and direction of future spending open. It is entirely possible that these shorter-term holders will become the engine of the next upward move, converting their coins into spending power at higher prices. It is equally possible that they will accelerate a sell-off if conditions deteriorate. The data does not make the decision for them; it only establishes that they have more capacity to react. And because exchange balances are excluded from the classification, the metric is designed to capture the broader network dynamics rather than the temporary movement of funds into trading venues. That makes the 14.2% figure a useful signal for anyone trying to understand whether Bitcoin’s supply is becoming more fragile in ways that open interest simply cannot capture.
Spot markets have provided at least a partial counterweight to that fragility. The report’s spot cumulative volume delta, or CVD, is a tool that tracks the balance between buyer-initiated and seller-initiated trades on spot exchanges. It is often used as a proxy for aggression, showing which side of the market is exerting more pressure at any given moment. In this latest snapshot, CVD moved from negative $102.8 million to positive $33.2 million. That swing is meaningful because it suggests the balance of spot trading activity has tilted away from sellers and toward buyers. A period of net selling pressure has given way to modest net buying pressure, which can help absorb some of the supply that shorter-term holders might be inclined to release. But Glassnode cautions that this improvement does not necessarily mean new investor capital is flooding into the market. The measure tracks trading aggression, not the origin of the capital behind the trades. It could reflect buying by existing players, positioning by market makers, or the same coins moving between different entities in a way that creates the appearance of demand. That is not to diminish the change. A shift from negative to positive CVD is still a notable development, especially when it occurs alongside a contraction in derivatives exposure. It provides a counterweight to the risk of more sensitive short-term supply, because it hints at a spot bid ready to absorb sales. But the measure is not a crystal ball. It does not quantify the size of the new money, nor does it guarantee that buying pressure will continue. The improvement is a snapshot of trading behavior over a limited window, and in a market as fast-moving as Bitcoin, those windows can shut quickly.
Taken together, the data paints a picture of a market in a delicate balance. Futures exposure and holder activity must be read together, because each one tells a different part of the same story. The October snapshot shows a smaller nominal derivatives footprint alongside more recently active capital, with improving spot buying providing a counterweight. That is a more hopeful combination than a market with rising open interest, fragile holder supply, and declining spot demand. But it is not a clean bill of health. The next test is whether continued demand can absorb active supply. Sustained spot buying would temper the fragility concern, while renewed taker selling alongside deteriorating holder profitability would strengthen it. There is also the lingering question of leverage. Even with open interest lower, the rise in long-side funding payments suggests that the remaining derivative positions are not risk-free. If the market turns down, those positions could cascade, and the growing presence of short-term holders could add fuel to the fire. The reverse is also true: if spot buyers keep stepping in, the market could absorb that supply and push prices higher. Glassnode’s overarching message is that vulnerability in Bitcoin markets is not a single line on a chart. It lives in the interaction between derivatives positioning, holder behavior, and spot market flow. For professional traders, that means watching all of these metrics together rather than latching onto one headline number. For observers, it is a reminder that the crypto market’s risk profile is rarely as simple as it seems. The shrinking open interest numbers were real, but so were the rising funding payments, the increasingly sensitive holder base, and the flicker of buying pressure on spot exchanges. Any one of those signals can be misleading on its own. Together, they tell a much more complex story — and one that is still being written.